

Live now
Index readings from the same feed the Sahi terminal runs on. Open the live GEX Levels to see this guide applied to today’s numbers.
- NIFTY — —
- BANKNIFTY — —
- SENSEX — —
Read the Page in About Two Minutes
How do I open the page and read one verdict, one level and one caution from it in about two minutes?
Gamma Exposure, written GEX on the page, is an estimate. It asks: if the people on the other side of the public's option trades (the page calls them dealers) hedge what they hold, will their hedging lean against the price's moves or run with them? The page works this out strike by strike from the option chain, adds the strikes up, and says the answer in a few words. Below are six steps. They take about two minutes. Nothing you do on the page changes any market or places any order.
Your First Five Minutes
- Open the page and change nothing. Read the row at the top: the verdict (Hedging dampens moves in the pictures), the Flip chip, the Net chip, and the text that says how far the price is from the flip.
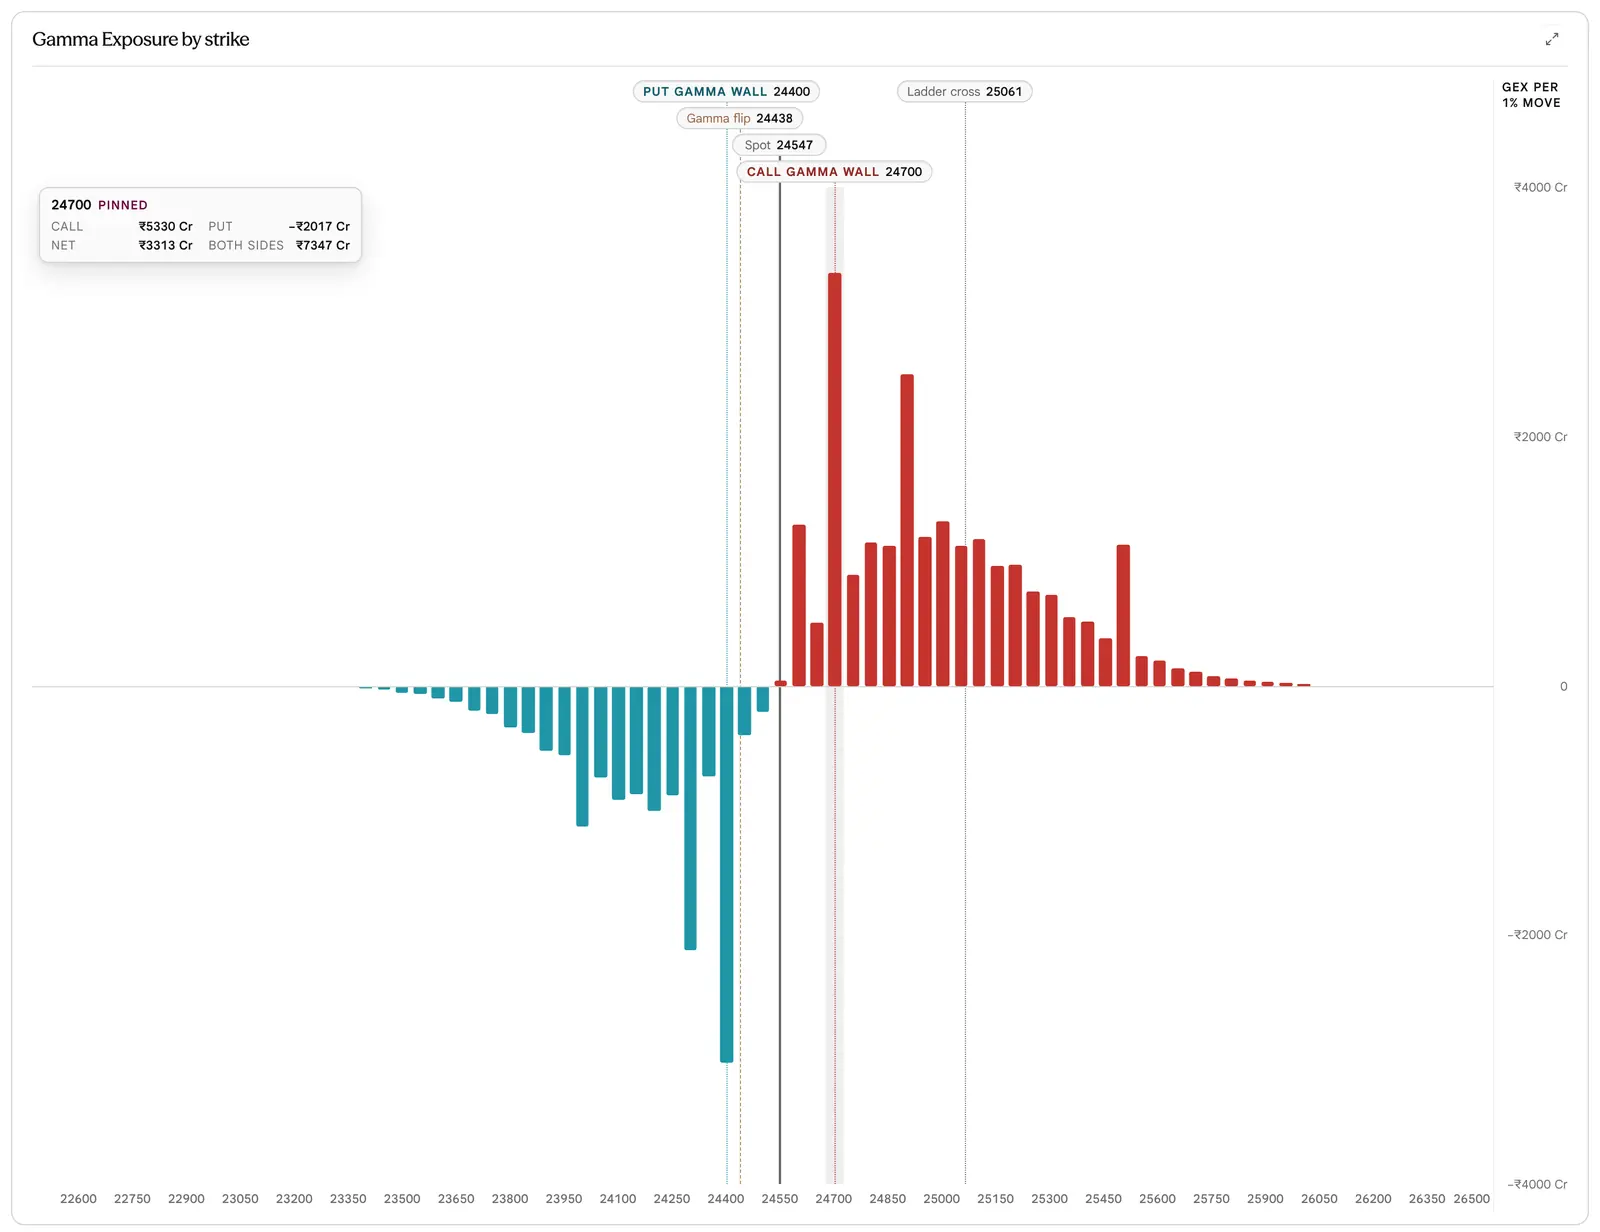
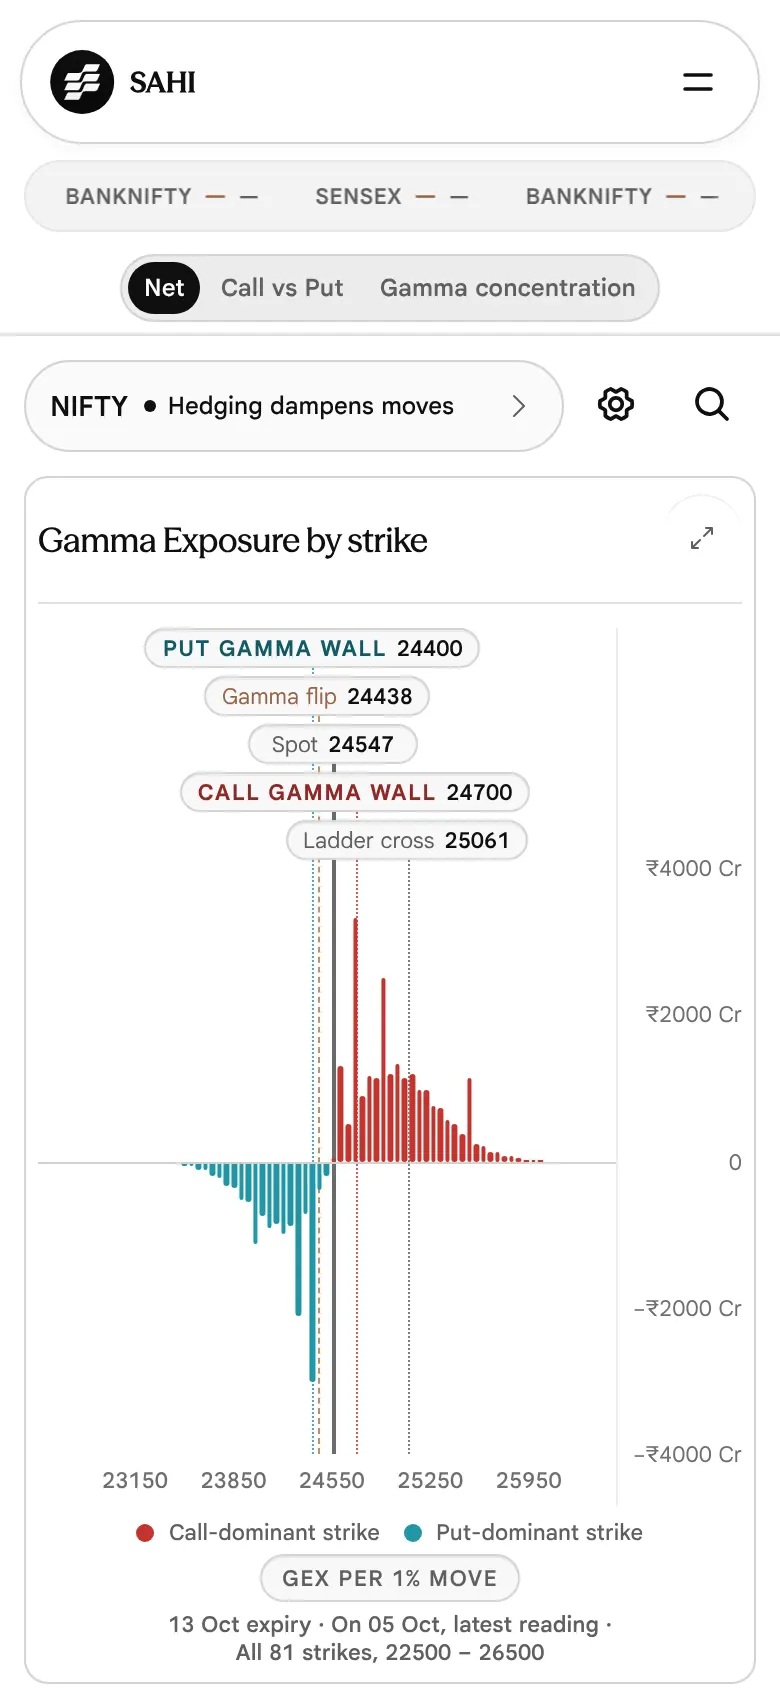
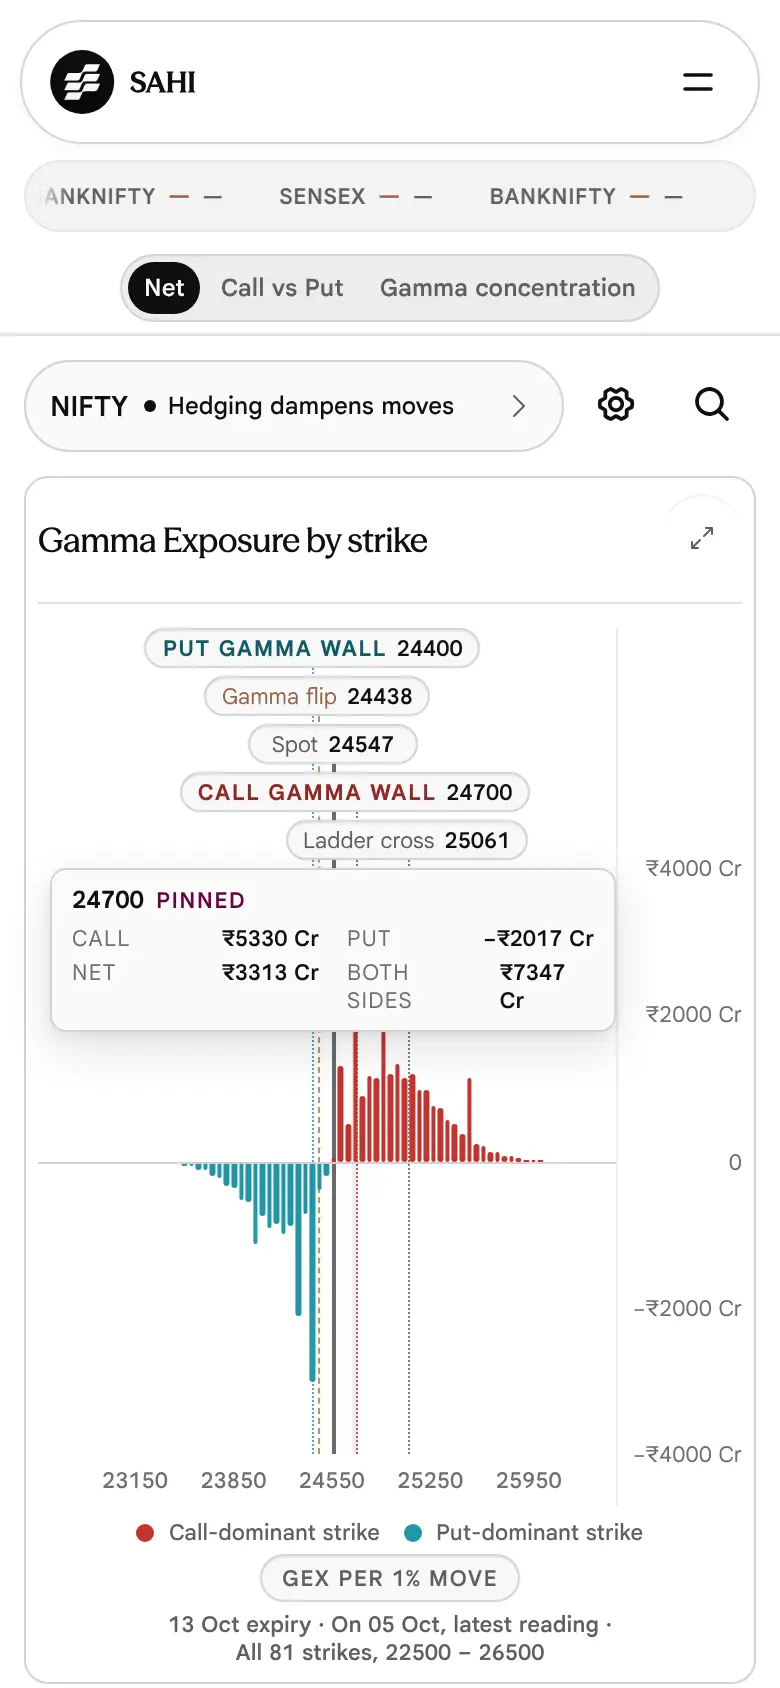
- Look at the bars. Each bar is one strike. Above the horizontal line the Call side outweighs the Put side at that strike; below it, the Put side does. The badges above the bars name the price, the gamma flip and the walls. On a phone the names sit in one row above the plot instead.
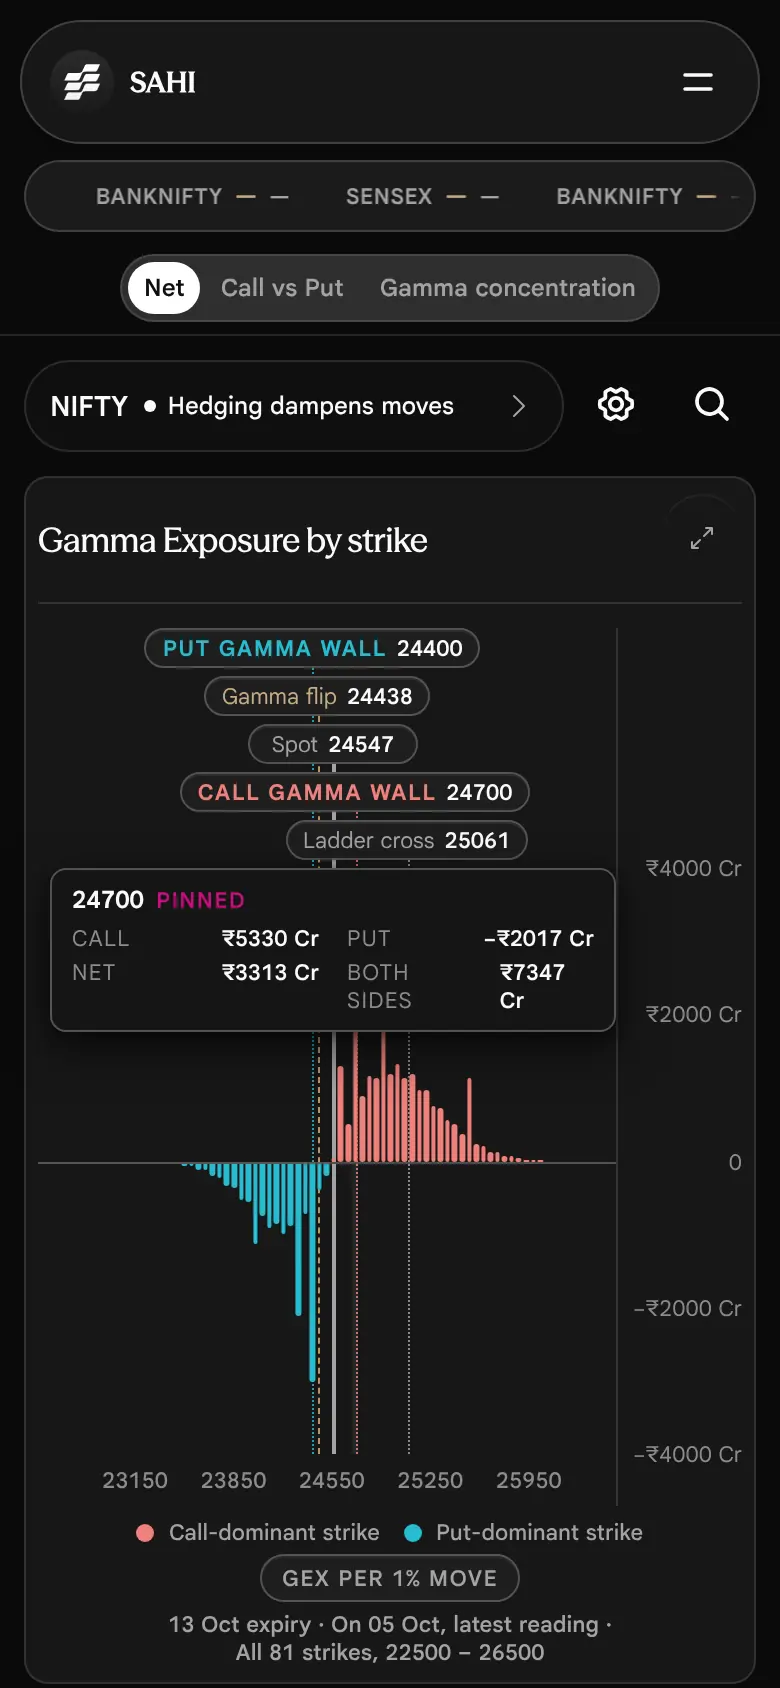
- Hold the mouse over a bar. A small card follows the pointer and gives the Call, Put, Net and Both sides figures for that strike.
- Open the insight with the arrow at the right end of the row. Read the first sentence, which says why, then the three under it: the levels, the change and the book. Read the first caution.
- Remember what the figure is. It rests on an assumption about who holds the contracts that exchange data cannot confirm. It describes modelled hedging. It does not say where the price will go.
-
Open the page
Open GEX Levels. In the app's list of workspaces it is named GEX Levels, between Straddle and Implied Volatility. It opens on the symbol you last looked at (NIFTY in the pictures), on the nearest expiry, with all 81 strikes of the expiry drawn.

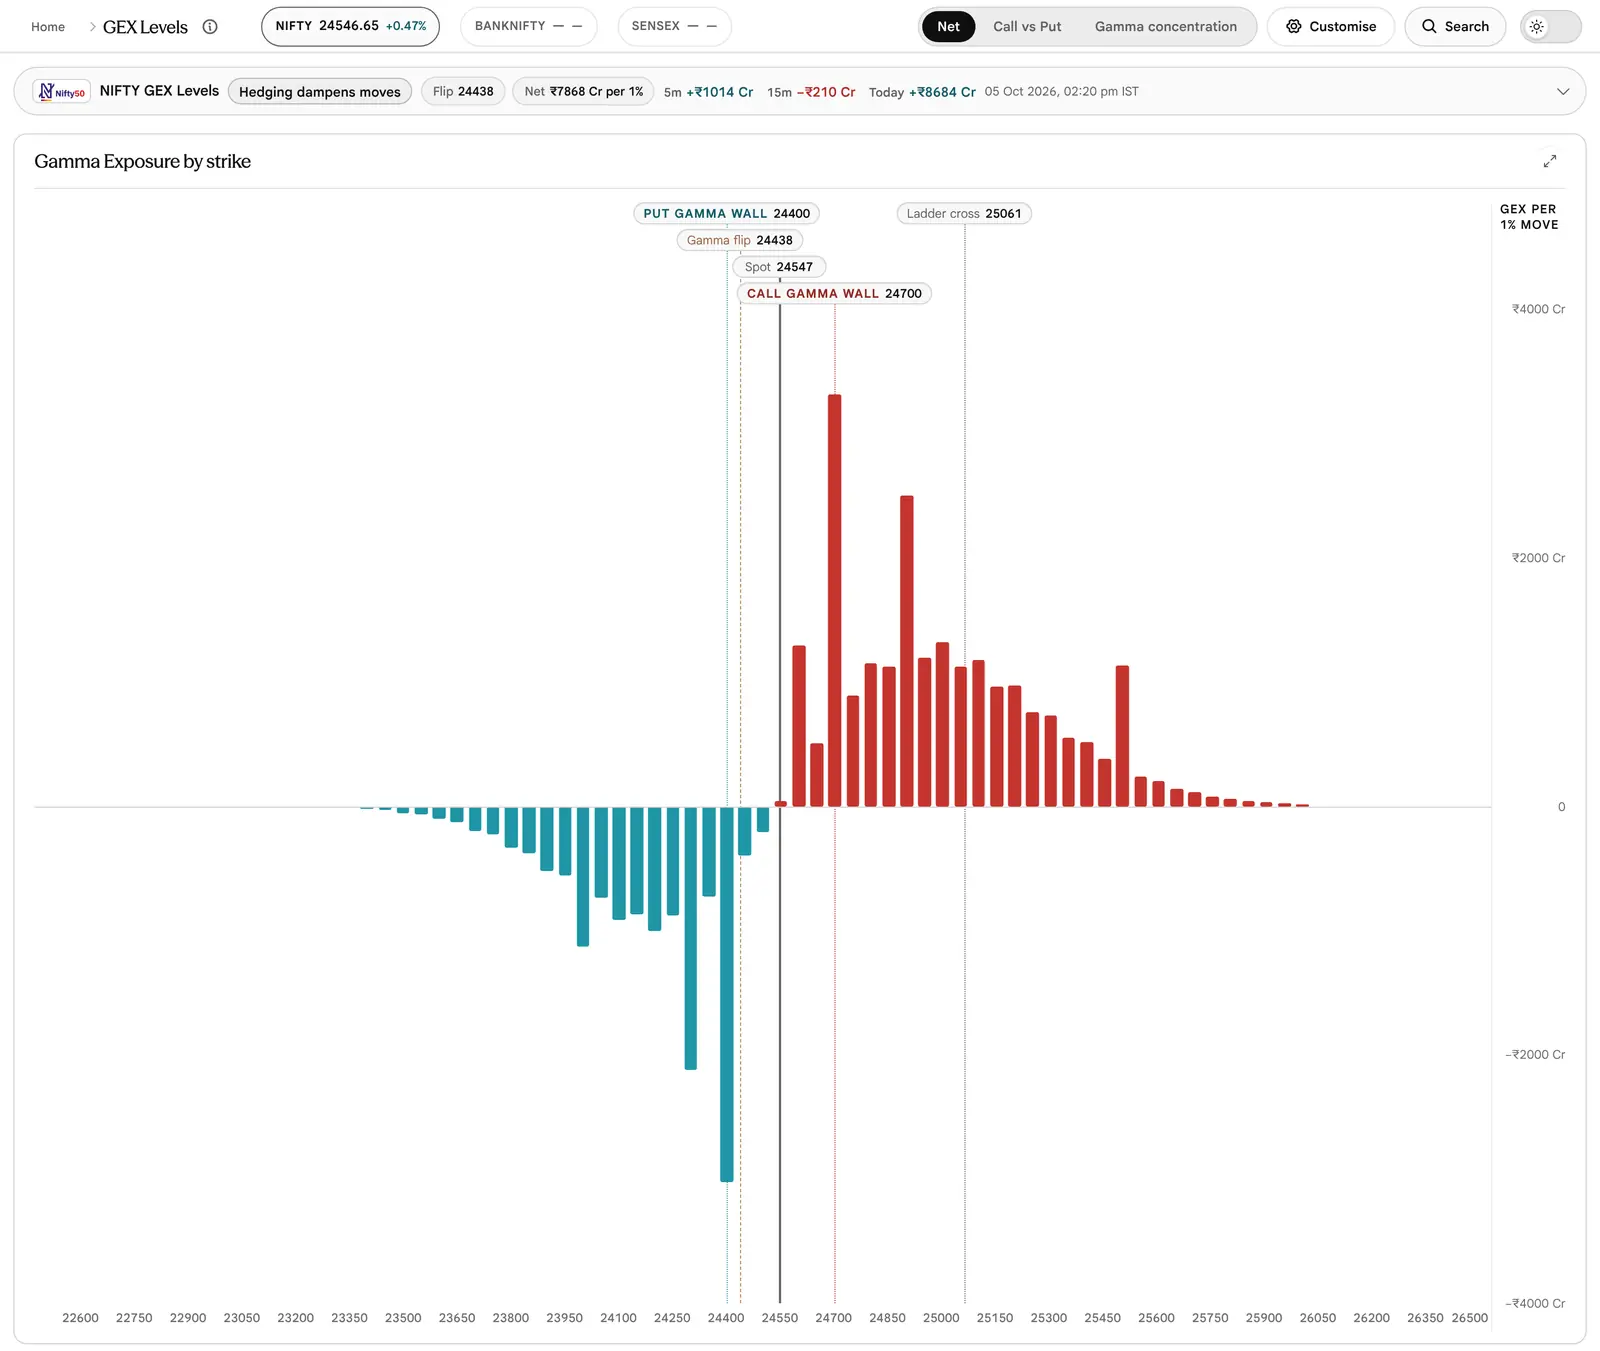
Look at: the row at the top first, then the badges above the bars, each joined to its own vertical rule, then the bars. The wall badges now read Call gamma wall and Put gamma wall in sentence case. (Picture taken before the page changed on 19 October 2026: picture not retaken.) -
Read the row
The words, Hedging dampens moves, say what the modelled hedging would do. Flip 24438 is the price at which the model's total changes sign. Net ₹7868 Cr per 1% is the total, in rupees of hedging for a one per cent move. The three small figures, 5m, 15m and Today, are how far that total has changed. The text at the right says NIFTY is 109 points above the flip. The row, piece by piece.
-
Find the zero rule and the walls
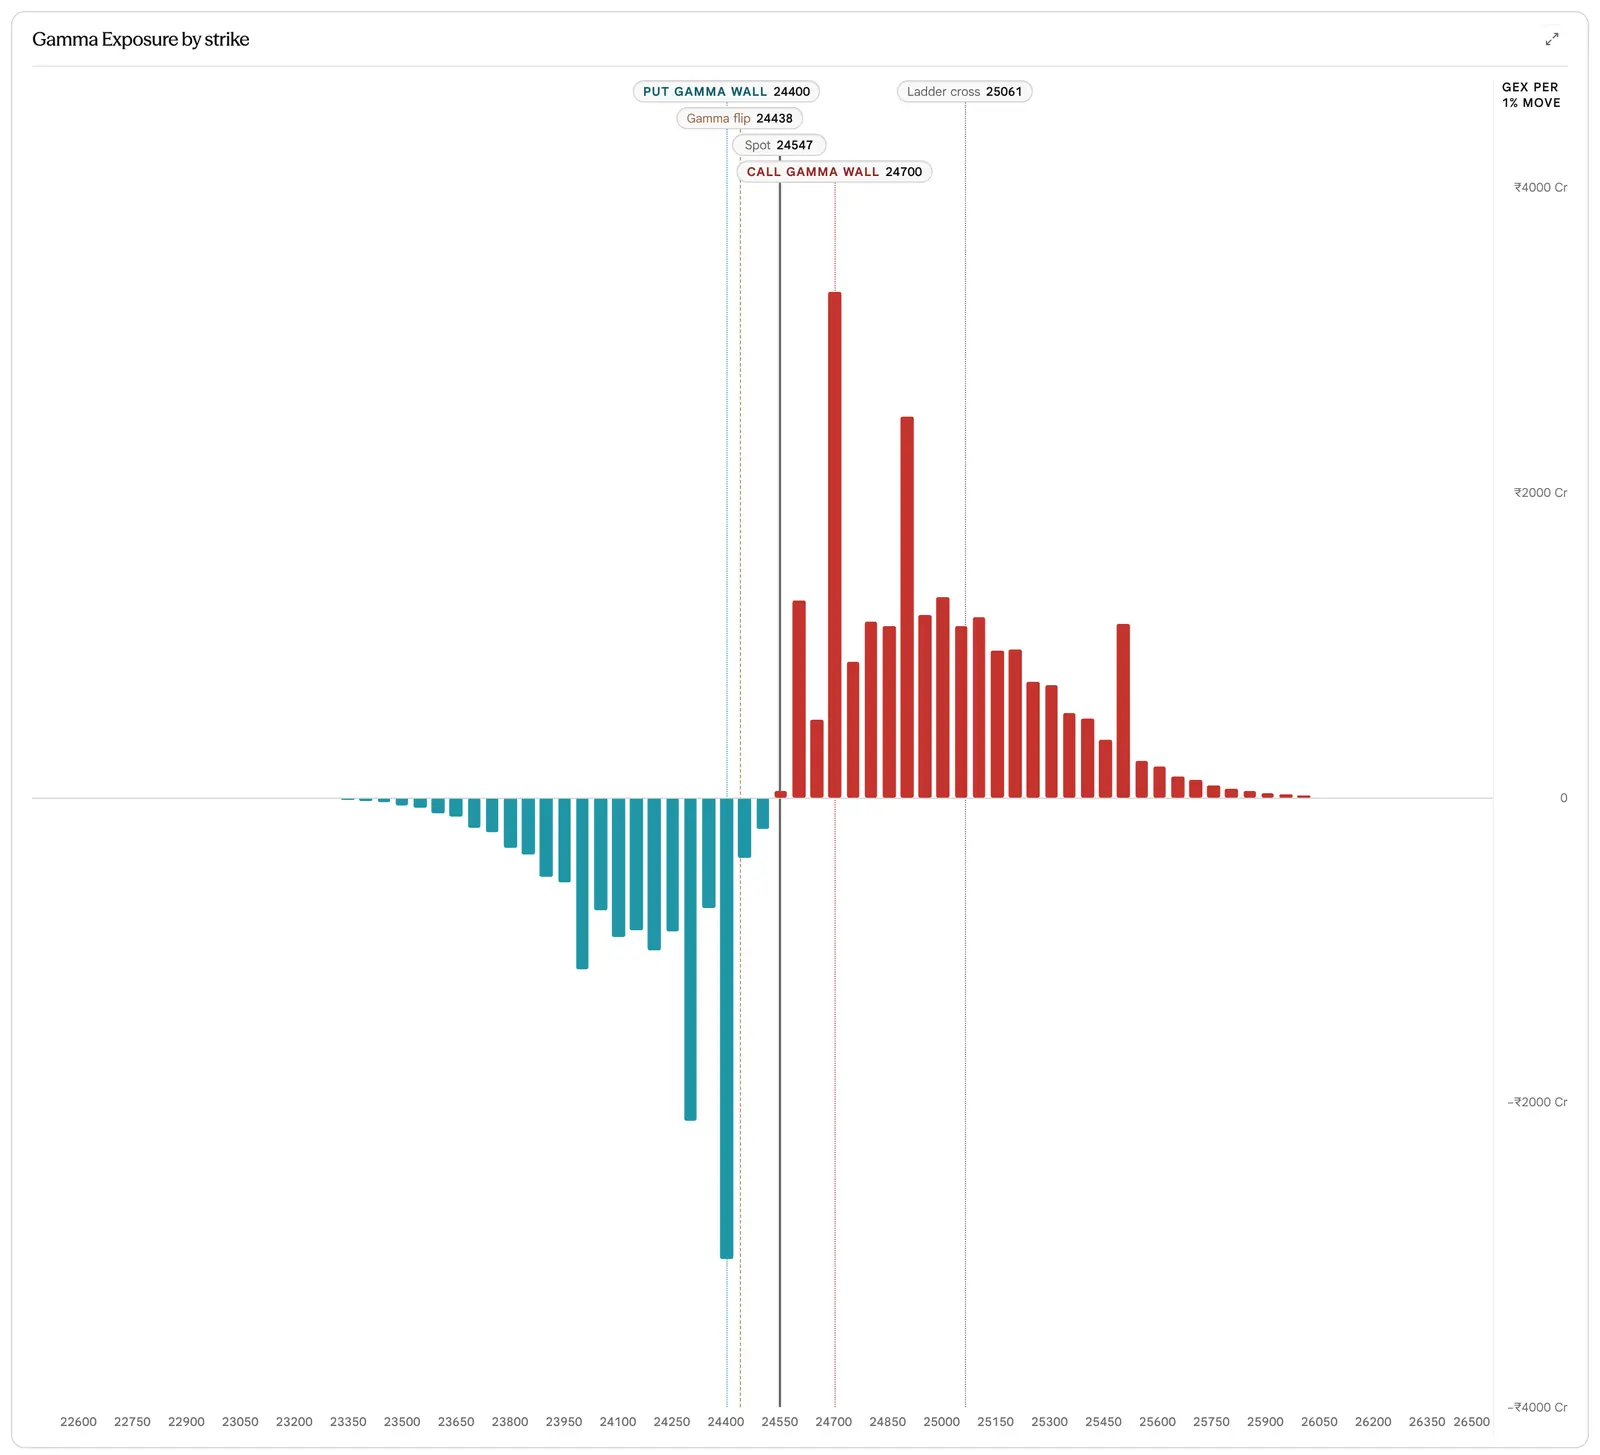
The bars grow from a horizontal line, the zero rule. Bars above it are strikes where Call exposure outweighs Put exposure; bars below it, the other way round. The Call gamma wall (24700) and the Put gamma wall (24400) mark the strikes, above and below the price, where the modelled hedging is thickest on each side. The levels.
-
Hold the mouse over a strike
On a desktop the readout moves with the mouse. On a phone, tap a bar and the readout stays in the corner of the plot. The readout.
-
Open the insight and read the first caution
Press the arrow at the right end of the row (a screen reader names it Show the full insight). The box gives four sentences, the reason first, and the first caution, which on every reading is the same: who holds each option is not published, and the model assumes dealers own the Calls and are short the Puts. Why that matters.
-
Put it beside other facts
The page is one fact about how open contracts would be hedged. The price, the Open Interest and the other pages show other facts. Routines for the morning, the session and expiry day show one way to use it.
Which Parts to Read
New to options: read What Gamma Exposure is, what gamma is, the assumption underneath, common mistakes and the glossary. Already trade options: go to the formula, how the flip is solved, gamma walls against Open Interest walls and what it cannot tell you. Short of time: read this section and the insight box.
What Gamma Exposure Is
What is Gamma Exposure, and what will it not do for me?
The Seller Who Must Stay Level
Think of a dealer who has sold you an option. If the price moves, the option's value moves, and the dealer, who wants to stay level, buys or sells a little of the underlying to cancel it. That buying and selling is hedging. How much the dealer must trade for each move depends on how quickly the option's sensitivity changes. That quickness is gamma.
Gamma Exposure adds that up over every strike of one expiry and asks whether the hedging, taken together, would push the price back (positive) or push it further (negative). It is an estimate built on one assumption about who holds what. The page says so on every reading.
An option is a contract. A Call gives its holder the right to buy the underlying (an index such as NIFTY, or a share) at a fixed price, the strike. A Put gives the right to sell it. (The exchange's own codes, CE for Call and PE for Put, appear in some data files; this guide and the page write Call and Put.) Open Interest is the number of contracts at a strike that are still open. It counts positions, not trades.
What the Page Does
- It reads a saved reading of the option chain for one expiry and works out, for every strike, how much hedging the Calls and the Puts there would call for (where the data comes from).
- It draws that exposure strike by strike in three views, marks the gamma flip, the two gamma walls and the ladder cross, and draws a curve that shows where the total changes sign.
- It sums the picture up in one row with a verdict, and in an opened box with the reason, the change and the levels.
- It lets you choose the expiry, the strikes drawn, the lines drawn and a replay of the session, and it remembers some of those choices in your browser.
What the Page Does Not Do
- It does not know who holds the contracts. Exchange data records Open Interest, never the holders. The signs on the page come from an assumption, stated plainly in part A.
- It does not forecast the price. The verdict names what the modelled hedging would do, not where the price will go.
- It does not see hedges carried in other expiries. It reads one expiry at a time.
- It places no order and gives no advice.
Words Used Before They Are Explained
- Gamma
- How fast an option's delta changes as the price moves.
- Dealer
- Whoever holds the other side of the public's options and hedges it. The page assumes who they are; it cannot see them.
- Gamma flip
- The price at which the model's total exposure changes sign.
- Lakh and crore
- 100000 and 10000000. The page prints them as L and Cr, and writes money as ₹7868 Cr.
The Screen at a Glance
What is on the screen, and which part do I read first?
The page has these layers, top to bottom: the page bar, the insight row, the strike profile, and then the cards for the curve, the session and the table. Everything you can change is in one panel, Customise, at the top right, except the plot view, which sits beside it on the page bar.
- Page barHome, GEX Levels with its info button, the Plot view capsule (Net, Call vs Put, Gamma concentration) and the Customise button.
- Insight rowThe verdict, the Flip and Net chips, the 5m, 15m and Today change in Net, how far the price is from the flip, and the time of the reading.
- Gamma Exposure by strikeThe bars, the level badges above them, the strike rail and the value axis. On a desktop it runs to the bottom of the window with nothing under it. A phone puts a key row of level names above the plot, and the legend and the scope line below it.
- Where the sign changesThe curve that makes the gamma flip a visible crossing.
- Session cardsPrice against these levels, Price and strike levels, and Exposure through the session. They need two or more readings.
- Every strikeA table that restates every figure in words and numbers.


The Pieces of the Profile, Item by Item
| On the screen | What it stands for |
|---|---|
| A bar | One strike. Its height is rupees of hedging per one per cent move, on the value axis at the right. The three views. |
| The zero rule | The horizontal line the bars grow from. It is not drawn in the Gamma concentration view. |
| Spot | The price of the underlying at the reading. When it is within one strike step of the flip, the two badges merge into one that reads Spot at flip. |
| Gamma flip | The price at which the whole model's total changes sign. Solved, not read off the bars. |
| Ladder cross | The strike where the running total of Net, added from the lowest strike up, crosses zero. A different level from the flip. |
| Call gamma wall, Put gamma wall | The strike above the price with the largest Call gamma exposure, and the strike below it with the largest Put gamma exposure. Not the strikes with the most Open Interest. On a phone the key row shortens them to Call wall and Put wall. |
| GEX per 1% move | The unit: rupees of hedging for a one per cent move in the underlying, printed as ₹ Cr or ₹ L. It heads the value axis. |
| The scope line | On a phone, one sentence under the plot naming the expiry, the reading and the strikes drawn, for example All 81 strikes, 22500 – 26500. A desktop leaves it out, and shows it only while the replay is on an earlier reading. |
The question each topic answers (5 topics)
- What is gamma, and why would anyone hedge more or less as the price moves?
- What exactly is multiplied to get the figure for one strike, and what does each factor do?
- Who is assumed to hold the Calls and the Puts, why can no one confirm it, and what changes if it is wrong?
- Where does the gamma of each strike come from, and when does the page decline to give a figure?
- How are the strikes added up, what is the lean, and when does the page name a side?
What Gamma Is
What is gamma, and why would anyone hedge more or less as the price moves?
Speed and Acceleration
An option's delta is how many rupees its price moves for each rupee the underlying moves. Think of delta as speed. Gamma is how quickly delta itself changes as the price moves. Think of it as acceleration. An option with high gamma changes its sensitivity fast; one with low gamma hardly changes it.
Gamma is largest for options near the money and falls away as a strike gets far from the price. In the guide's invented book, the 24700 strike carries a gamma of 0.000857 with NIFTY at 24547. That means each one-point rise in NIFTY adds about 0.000857 to the delta of one unit of that option. The 25500 strike, far above the price, carries 0.000110, about one-eighth as much.
Why Hedging Follows Gamma
A dealer who sold options wants to stay level to small price moves, so the dealer holds some of the underlying (or a future) to cancel the options' delta. When the price moves, the delta moves, and the hedge has to be adjusted. The size of that adjustment depends on gamma, and its direction depends on whether the dealer is long gamma (owns the options) or short gamma (has sold them).
| The dealer's position | When the price rises | When the price falls | The page's words |
|---|---|---|---|
| Long gamma (net owner of options) | Delta rises, so the dealer sells some of the underlying. | Delta falls, so the dealer buys some back. | Hedging dampens moves: modelled hedging sells into rises and buys into falls, leaning against each move. |
| Short gamma (net seller of options) | Delta rises against the dealer, so the dealer buys. | Delta falls, so the dealer sells. | Hedging amplifies moves: the hedging runs with each move. |
This is the textbook picture (what we have not verified). The page does not observe any dealer. It models what such hedging would be if the open contracts were held in the way the next section describes. The word modelled appears in the page's own sentences for that reason.
Positive does not mean bullish. A positive total says the modelled hedging would steady the price. It says nothing about direction. The page prints the verdict in plain ink, not green or red, for that reason: it is a regime, not a direction.
The Formula, One Strike at a Time
What exactly is multiplied to get the figure for one strike, and what does each factor do?
For each strike the page works out two figures, one for the Calls and one for the Puts. They are the same recipe with opposite signs:
-
Gamma: one per strike
The Call and the Put at a strike share one gamma, worked out from the market price of the option (where it comes from). It is delta per point, so it is a small number: 0.000857 at 24700.
-
Open Interest: in units, not lots
Open Interest here is the number of units of the underlying the open contracts cover, which is contracts times the lot size. The page's own data already holds it that way, so the formula has no lot-size factor: multiplying by the lot again would inflate every figure many times over. At 24700 the invented book has 10325510 units of Call Open Interest, which is 158854 lots of 65, and 3906825 units of Put Open Interest, 60105 lots. (Lot sizes in the pictures are illustrative; what we have not verified.)
-
Price squared times 0.01: from delta to rupees per 1%
A one per cent move is 0.01 times the price in points. Over that move, delta changes by gamma times those points, per unit. A change of delta is a quantity of the underlying to buy or sell, and its rupee value is that quantity times the price. So per unit the rupees are gamma × (0.01 × price) × price, which is gamma × price² × 0.01. That is why the price is squared, and why the result is in rupees of hedging per one per cent move. A side effect worth knowing: because the price is squared, a figure for a higher-priced underlying is larger for the same gamma and Open Interest.
-
Add the sign
Calls are counted positive and Puts negative, the convention explained next. Net is then the Call figure plus the Put figure.
One Strike Worked in Full (Illustrative)
The strike 24700 on the invented NIFTY book at 2:20 pm on 5 October 2026, with NIFTY at 24546.65:
A crore (Cr) is 10000000 rupees, so 53300122454 rupees is ₹5330 Cr. The page prints the same four figures when you hold the mouse over the 24700 bar. Its detail panel prints this very working under Strike 24700, worked, with the rule beside it: “Γ is per point of the underlying; Open Interest is in units, never multiplied by the lot again”. A table under it lists the gamma and both Open Interest figures for the 21 strikes nearest the price, so you can check any row yourself.


Check the Scale Yourself
The Sign Convention, and the Assumption Nobody Can Confirm
Who is assumed to hold the Calls and the Puts, why can no one confirm it, and what changes if it is wrong?
Read This Before You Trust Any Sign
The page counts every Call as positive and every Put as negative. That is the same as assuming that dealers own the Calls and are short the Puts in the open book. The page says so itself, on every reading: “Who holds each option is not published: the model assumes dealers own the calls and are short the puts.”
This is not something we can confirm, and it is not something you can confirm from exchange data either. Every open contract has a buyer and a seller. Open Interest counts the contract once. It does not say whether the buyer is a dealer, a fund or an individual, or whether a trade opened a position or closed one. So the assumption is a choice of convention, stated plainly, and every signed figure on the page (the Net, the verdict, the colours of the bars) rests on it.
What Changes if the Assumption Is Reversed
Suppose, for argument's sake, that the real book were the mirror image: dealers short the Calls and long the Puts. Every sign would turn over. This table works that out from the formula; it is reasoning, not a feature of the page.
| On the page | If every sign were reversed | Why |
|---|---|---|
| The verdict (Hedging dampens moves) | Changes: dampens would read amplifies, and the other way round. Near balance stays. | The verdict follows the sign of Net. |
| Net (₹7868 Cr) | Changes sign: ₹7868 Cr would be −₹7868 Cr. | It is Call minus Put. |
| The lean (21%) | Stays. | It is a size, the share of exposure that survives netting. |
| The gamma flip (24438) | Stays. | It is where the total is zero, and a total that is zero stays zero when every sign turns over. |
| The gamma walls and the heaviest strike | Stay. | They are found from the size of exposure on each side, not from its sign. |
| Gamma concentration (Both sides) | Stays. | It adds the two sides instead of subtracting them. |
The Assumption Can Fail in Other Ways
A reversal is the simplest failure. There are others that are not a clean mirror image. If dealers held the same side of both the Calls and the Puts, the modelled total would never change sign at all, and there would be no real flip to find. If different dealers are in different positions in different strikes, the sum hides it. The page cannot tell any of these apart, because Open Interest does not carry the information.
What Survives the Doubt
The page's own words for its Gamma concentration view are that it is “the one reading here that survives if that assumption is wrong. It shows where hedging would be heaviest, not which way it would lean.” It still depends on the model that produces the gamma, and on Open Interest being a fair count of contracts at each strike, but it does not depend on who holds them. The three views.
Where Each Strike's Gamma Comes From
Where does the gamma of each strike come from, and when does the page decline to give a figure?
The page does not read a gamma from the data provider. It reads, for every strike of one saved reading of the chain, the last traded price and the Open Interest of the Call and the Put, the price of the underlying, the expiry and the time of the reading. Everything else is worked out on the page's own code.
-
Form the forward
From the Call and Put prices at the strikes nearest the price, the page works out a forward, the price the market implies for the underlying at expiry (put-call parity, averaged over up to three strikes). In the pictures it is 24581.90. If no usable forward can be formed, or it is more than 3% from the price, the page solves on the price itself and adds a caution. The caution says that, on the real ladders checked, this made Net 55 to 65% smaller than the figure solved on the forward, and that every other figure moves as well.
-
Solve a volatility for each strike
For each strike the page takes the out-of-the-money option, the Call above the forward or the Put below it, because its price is all time value and so tells most about volatility. It finds the volatility at which an option-pricing model reproduces that last traded price. If that leg has no price, it tries the other leg. If neither has a price, it uses the volatility the data provider quotes for the strike, if there is one. If there is none, the strike is Not measured and contributes nothing.
-
Compute one gamma
From that volatility, the forward, the time left to expiry and a fixed interest rate of 6.5% (a setting of the app, printed in the detail panel's Data and scope section, not a market rate; what we have not verified), the page computes a single gamma for the strike. The data provider's own gamma column, which the Option Chain shows, is never used here.
-
Check that enough of the book carries a gamma
The page works out what share of all Open Interest sits at strikes that got a gamma. Below 60% it will not offer a total. At 95% or more the insight counts the coverage check as passed; between the two it shows the total with a caution naming the share left out.
When the Page Declines to Give a Figure
The page prefers a sentence to a wrong number. It says Not measured, and gives the reason in words, in these cases:
| Situation | What the page says (the cause it names) |
|---|---|
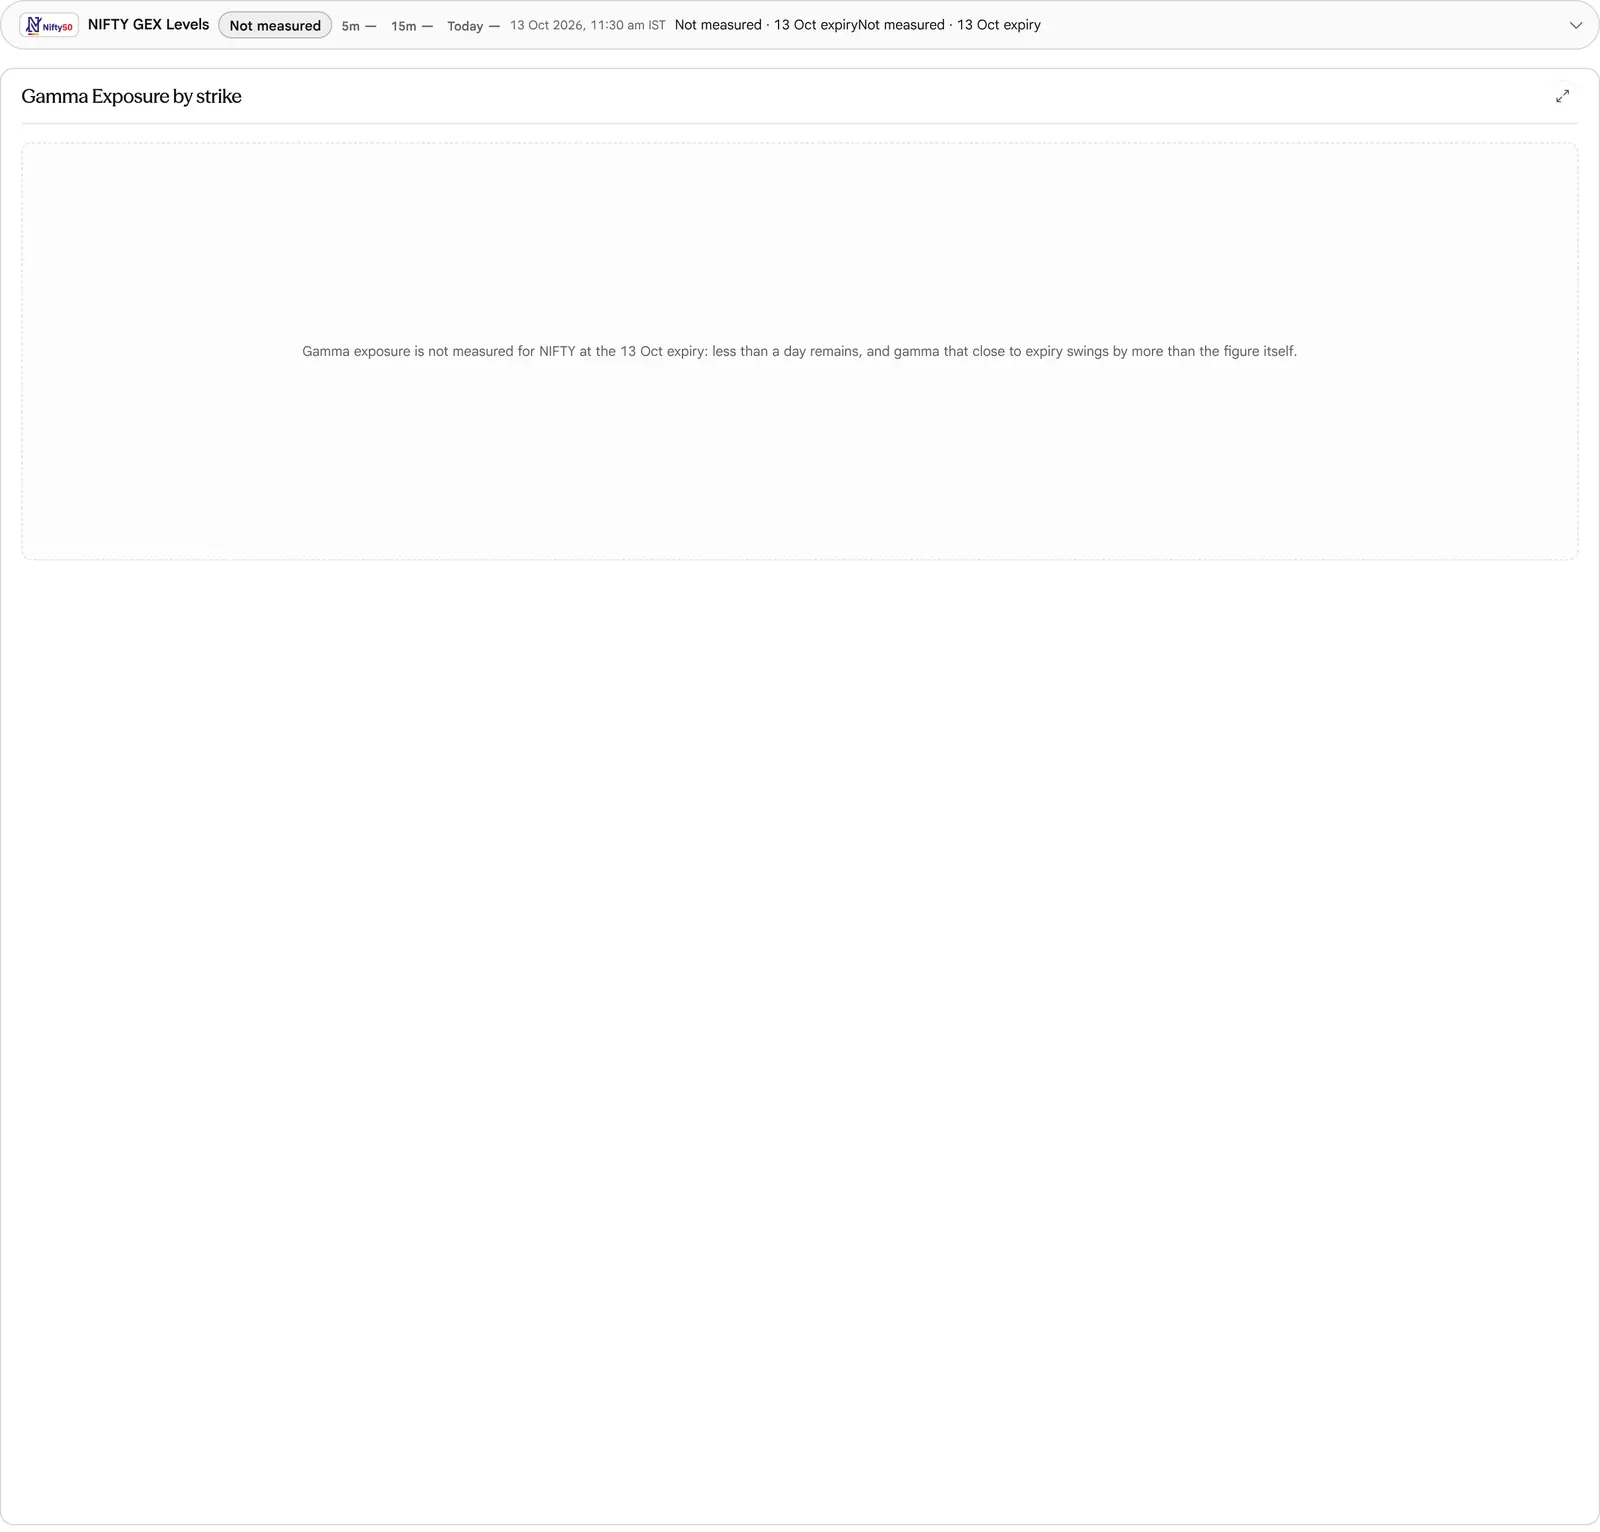
| Less than 1 day to the expiry | “less than a day remains, and gamma that close to expiry swings by more than the figure itself” |
| The series has already settled | “the series has settled, so its options no longer carry gamma” |
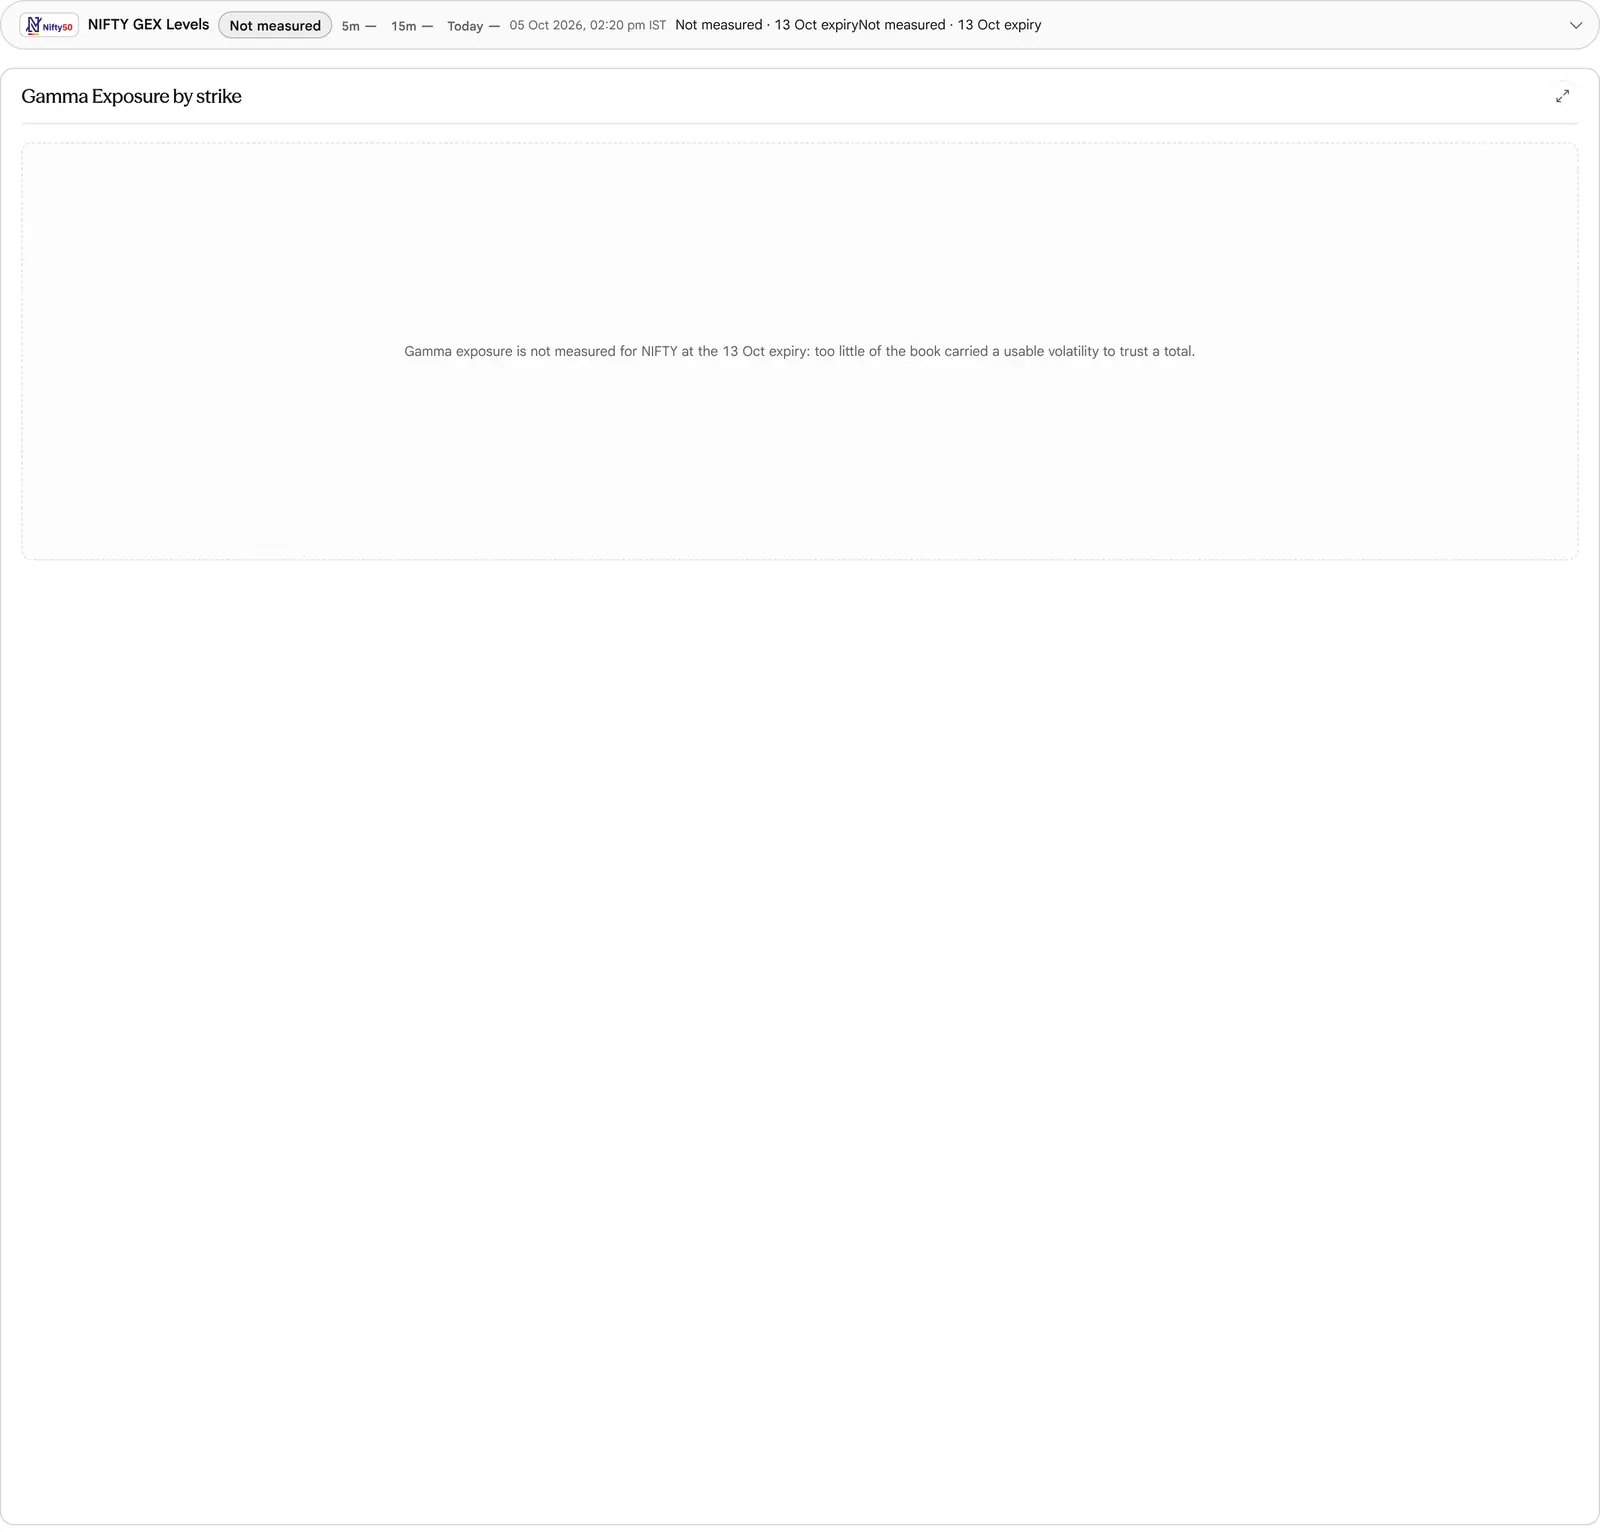
| Under 60% of Open Interest has a gamma | “too little of the book carried a usable volatility to trust a total” |
| No strike has a price that identifies a volatility | “no strike on this ladder carried a price that identifies a volatility” |
| No contract carries Open Interest yet | “no contract on this ladder carries open interest yet” |
The states, with pictures. Because the rule uses the time to expiry, the page withholds its figures for the whole of expiry day, from 15:40 the day before: the routines say what to use instead.

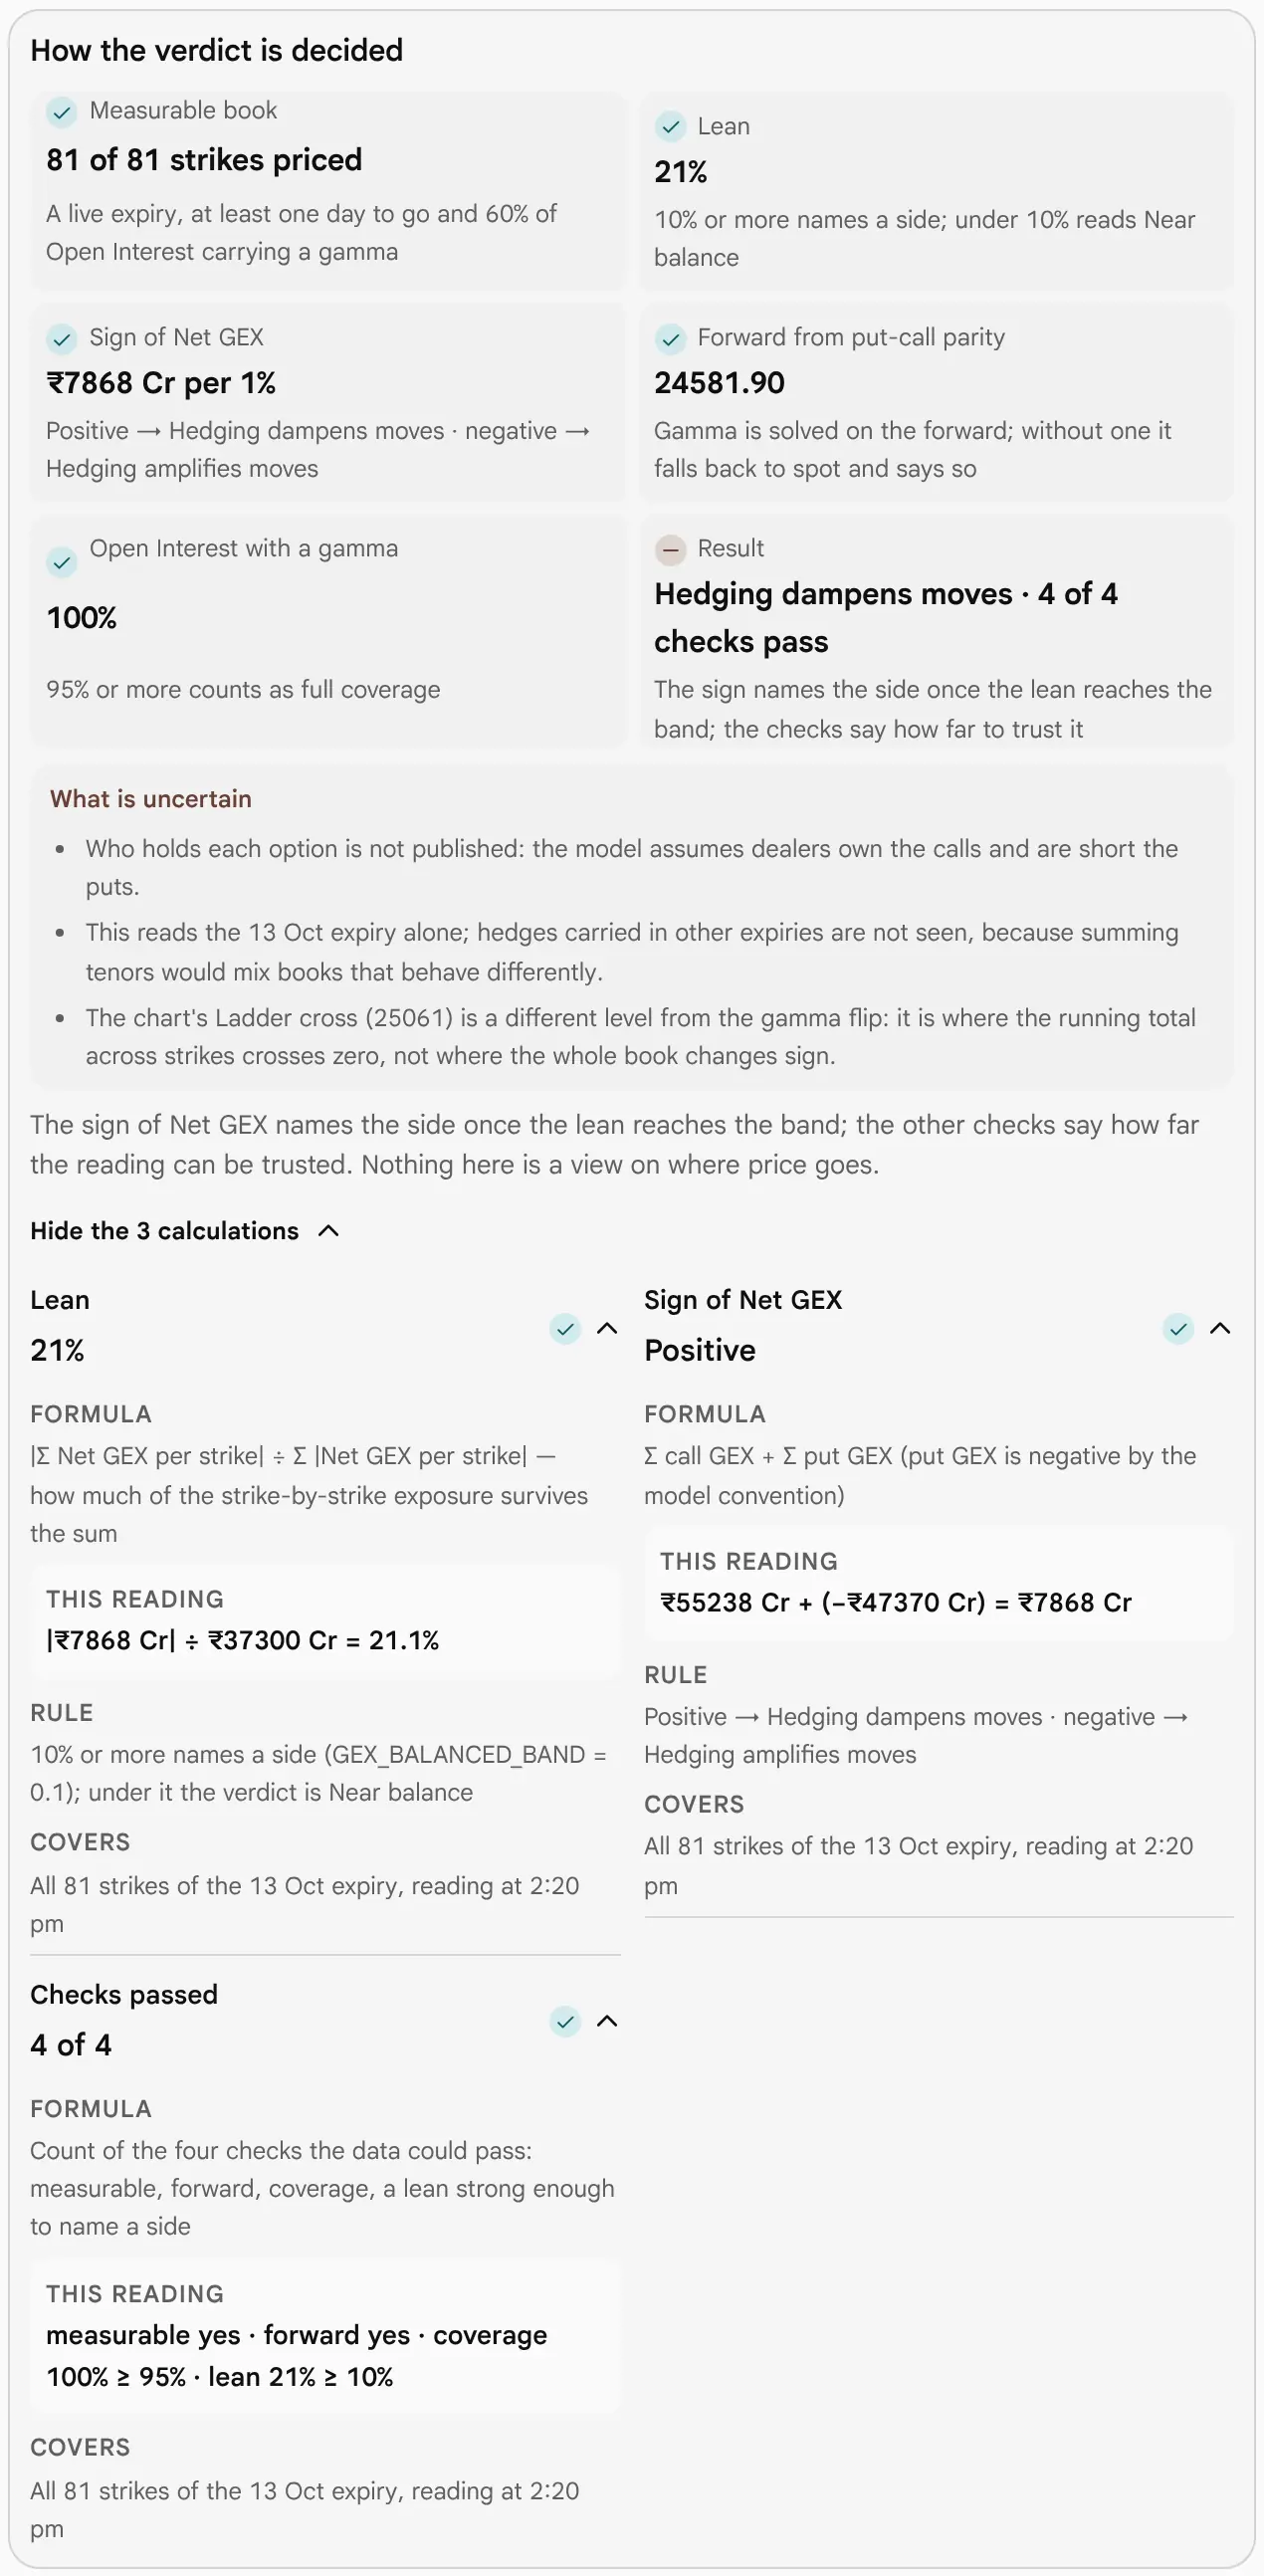
Adding the Strikes Up: Net, the Lean and the Verdict
How are the strikes added up, what is the lean, and when does the page name a side?
Once every strike has its Call, Put and Net figure, the page adds each column over the whole ladder (every strike of the expiry, not only the strikes drawn):
The Lean
A bare sign test would call almost every book positive or negative, even when the strikes nearly cancel. The lean asks a better question: of all the exposure that shows at individual strikes, how much survives when the strikes are added together? It is the size of Net divided by the sum of the sizes of each strike's Net, between 0% and 100%. A lean of 21% says about a fifth of the strike-by-strike exposure survives. A lean near 0% says the strikes cancel almost exactly.
The page names a side only when the lean reaches 10%. Under that it says Near balance. Within one point of 10% it prints one decimal and truncates toward the band, so that a lean of 9.96% is never printed as 10% beside the words Near balance.
The Four Verdict Words
| The page says | When | What it means in the model |
|---|---|---|
| Hedging dampens moves | Net is positive and the lean is 10% or more | Modelled hedging sells into rises and buys into falls: it leans against each move. |
| Hedging amplifies moves | Net is negative and the lean is 10% or more | Modelled hedging buys into rises and sells into falls: it runs with each move. |
| Near balance | The lean is under 10% | Calls and Puts nearly cancel; the page declines to name a side. |
| Not measured | The book cannot be measured (the cases above) | No figure, and a sentence saying why. |
The verdict is a standing level: it describes the book at the reading you are looking at. The Measured over window (the insight box) changes only the change line, never the verdict.
How the Figures Are Printed
Money is written as ₹7868 Cr (crore) or ₹1.5 L (lakh), with no digit grouping and a true minus sign. All the Net figures in the box are printed to one step chosen from the size of the reading: whole crore from ₹1000 Cr, a tenth of a crore below that, a tenth of a lakh for a small stock book. The changes are worked on the printed figures, so the arithmetic on the screen always adds up. In the pictures the 15 min change reads ₹7868 Cr − ₹8078 Cr = −₹210 Cr.
The question each topic answers (6 topics)
- What does each bar, badge, axis and line of the main chart mean, and what do the three views change?
- How do I read the exact figures for one strike, with a mouse, a finger or the keyboard?
- What is the curve under the bars, and why is the flip read from it rather than from the bars?
- What are the gamma flip, the ladder cross, the gamma walls and the heaviest strike, and how is each found?
- What do the three session cards show, when do they appear, and how does the replay move everything?
- Where do I find every figure in words and numbers, for the whole ladder?
The Strike Profile
What does each bar, badge, axis and line of the main chart mean, and what do the three views change?
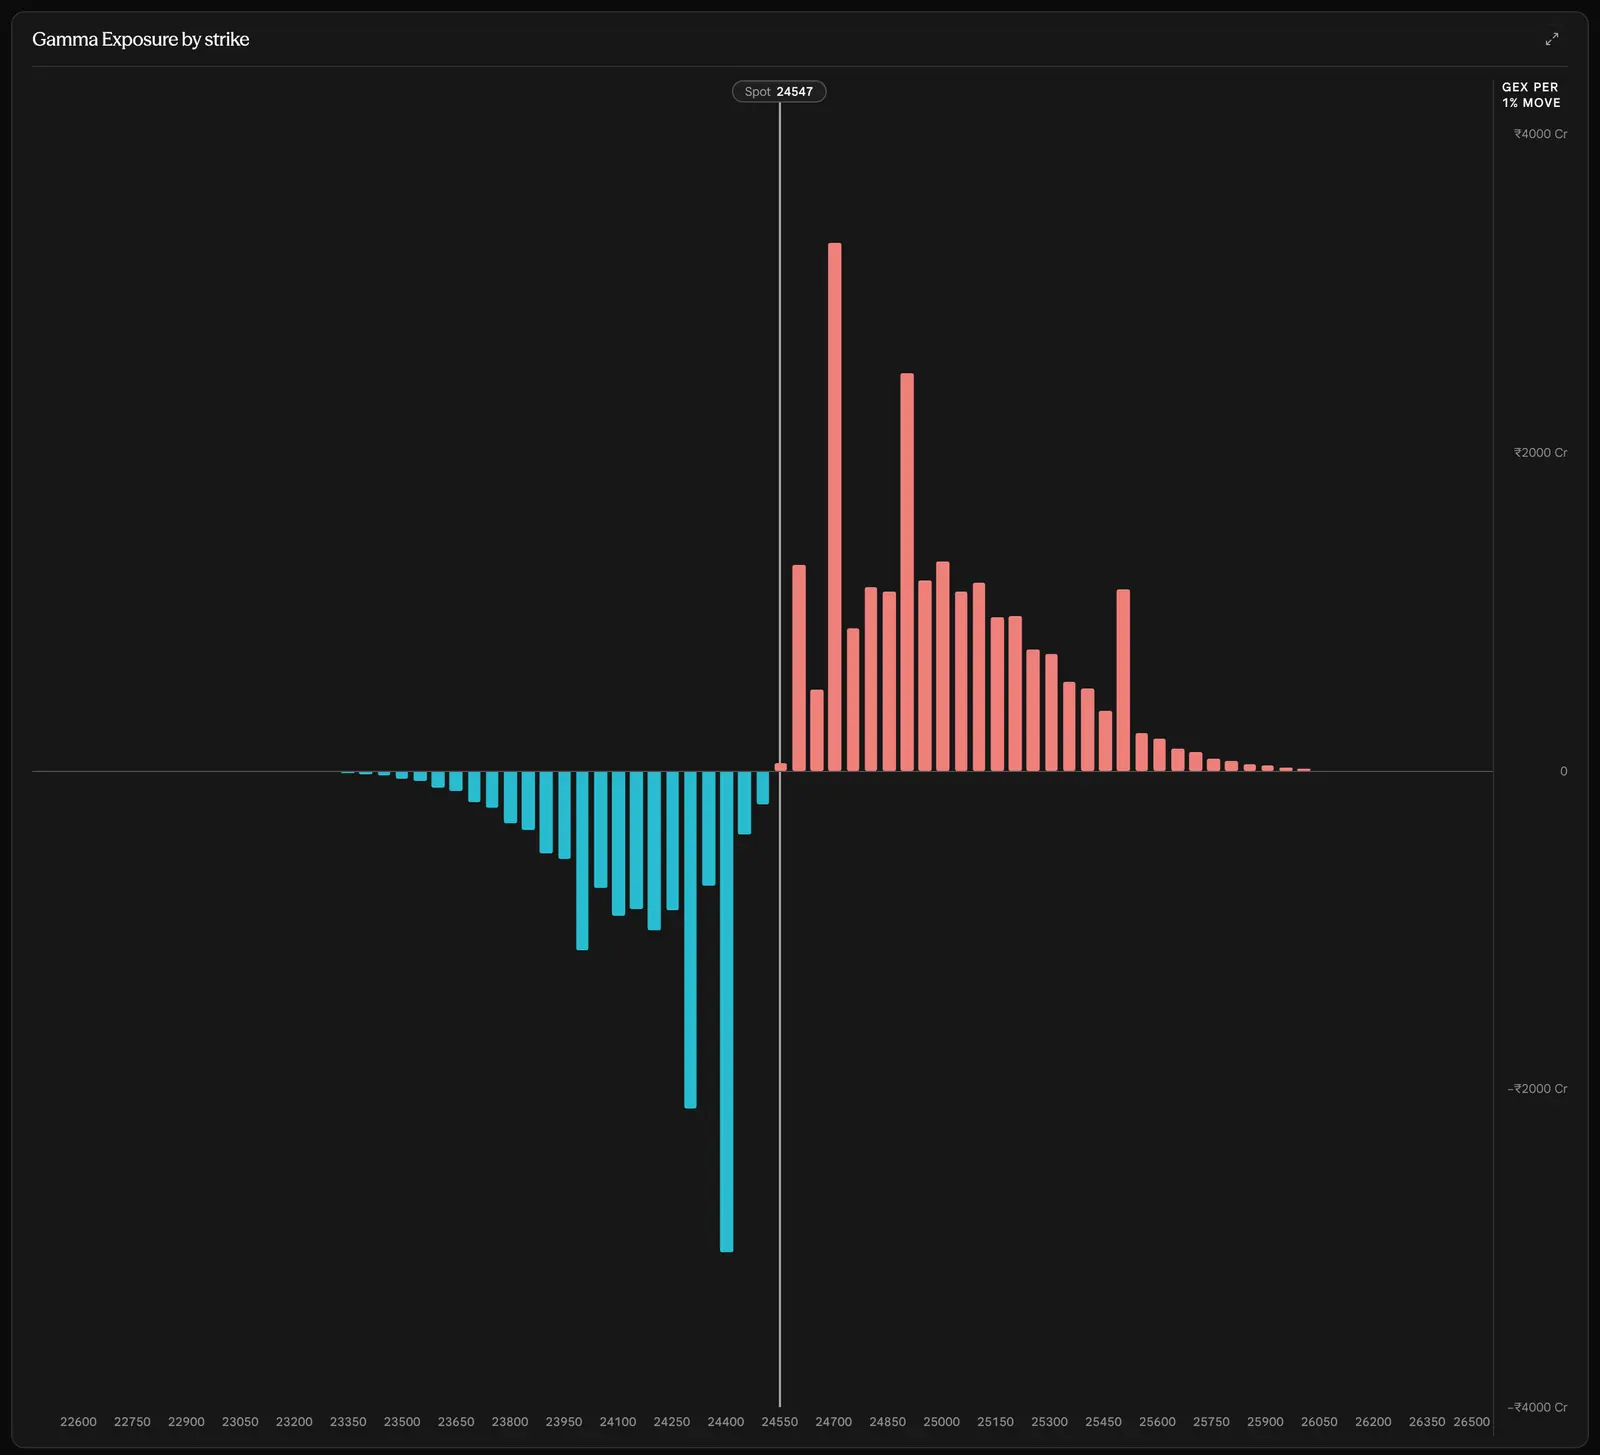
The card Gamma Exposure by strike draws one bar for each strike drawn: every strike of the expiry by default, or the count you choose in Customise, centred on the price. The strike is on the horizontal axis, lowest on the left, and the height of the bar is rupees of hedging per one per cent move, on the axis at the right. Three views, chosen on the page bar, draw the same ladder in three ways.
| View | What each bar is | Key under the chart (phone) | Depends on the holder assumption? |
|---|---|---|---|
| Net (default) | Call GEX plus Put GEX at the strike, from the zero rule, tinted by the side that owns it (call-dominant or put-dominant) | Call-dominant strike, Put-dominant strike | Yes: the sign comes from the convention |
| Call vs Put | Call exposure above the rule and Put exposure below it, each on the same scale | Call exposure, Put exposure | Only in the labels: the two sides are shown separately |
| Gamma concentration | Both sides added, rising from the floor, with no zero rule | Both sides added | No. The one reading that survives the assumption |


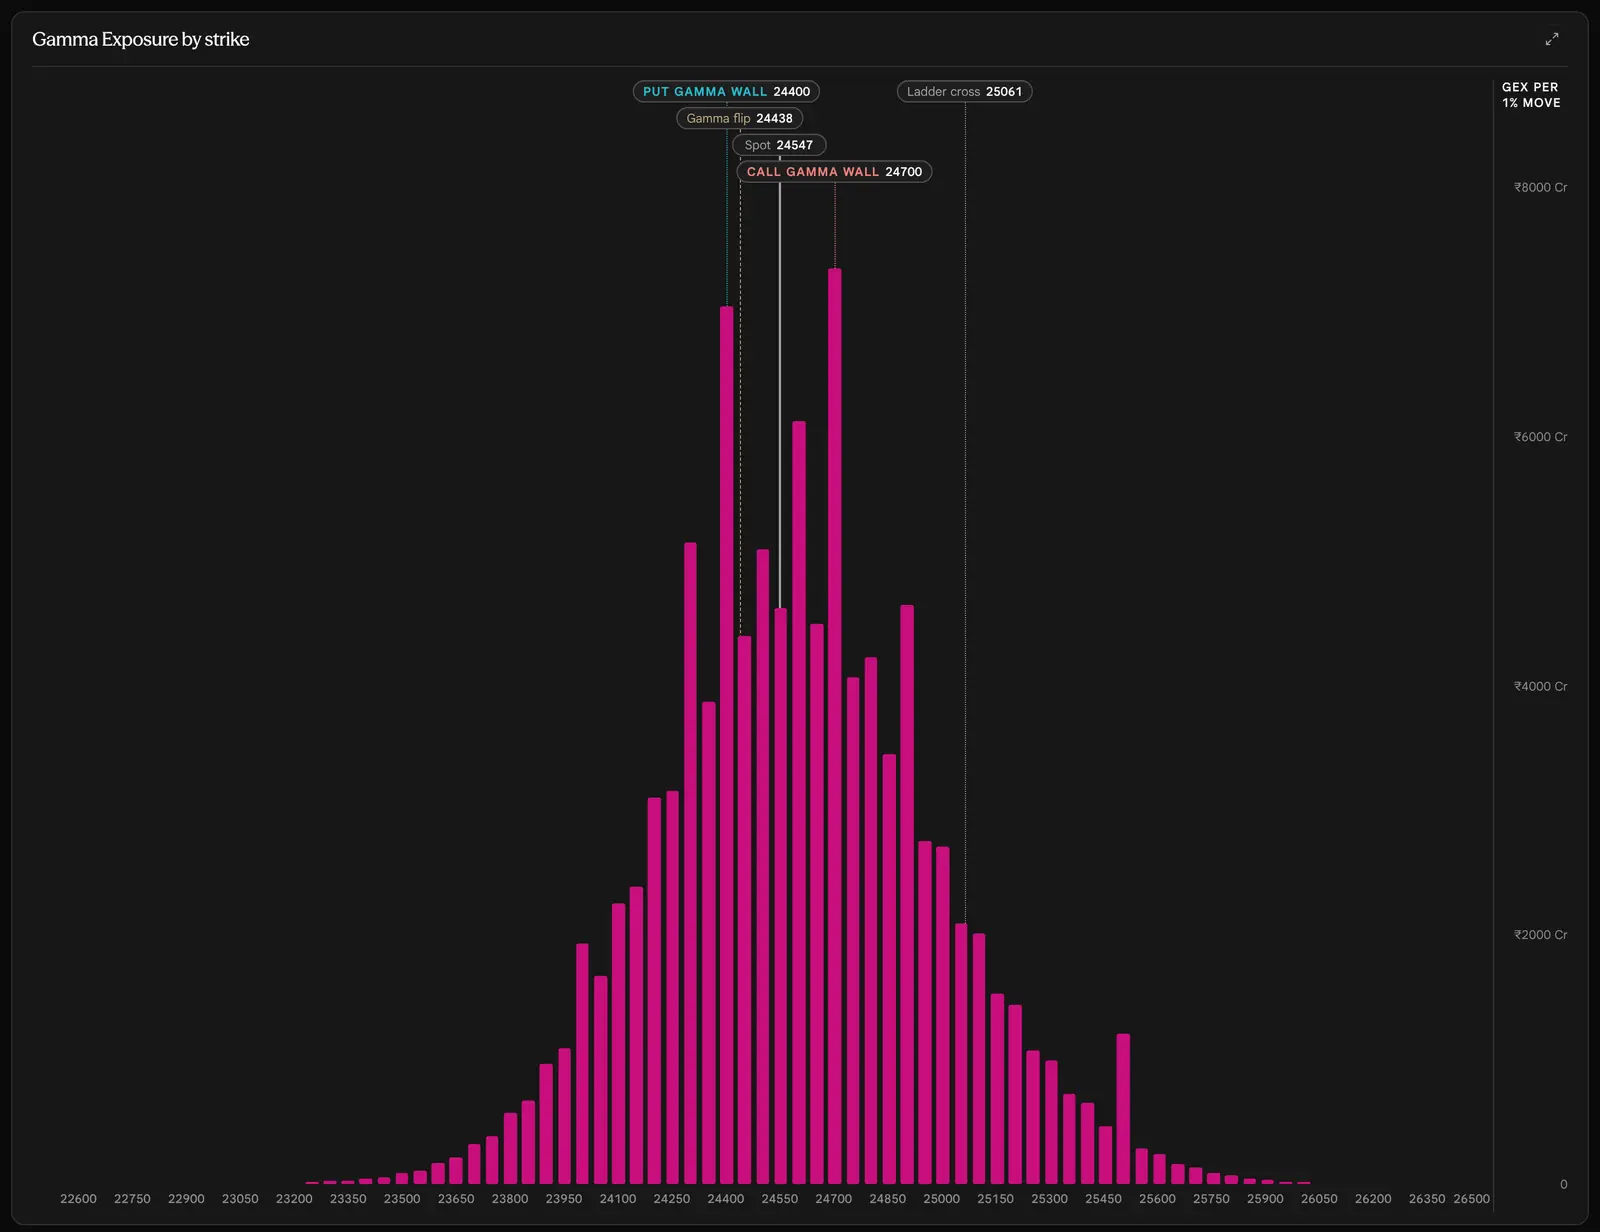

The Parts of the Plot
| Part | What it does |
|---|---|
| Colour of a bar | It names the leg that owns the strike (call-dominant or put-dominant). It does not mean bullish or bearish; the page says positive gamma is stabilising, not bullish. The legend (shown on a phone), the position of the bar and the Every strike table carry the same reading for anyone who cannot tell the two colours apart. |
| Level badges | Spot, Gamma flip, Ladder cross, Call gamma wall and Put gamma wall, in sentence case. On a desktop each badge sits in a band above the bars and is joined to a thin vertical rule at its own strike, which runs down to the strike rail. Badges that would overlap are placed on separate lanes. When Spot is within one strike step of the flip, the two merge into Spot at flip. |
| The key row (phone) | At 768 pixels wide or less there is no room for badges over the bars. The rules stay on the plot, and one row above the plot names them with short names and strikes, left to right in the order the rules fall. In the pictures it would read Put wall 24400, Flip 24438, Spot 24547, Call wall 24700, Cross 25061. Each name has a short stroke drawn like its rule. A merged badge keeps its name, Spot at flip. Reading it on a phone. |
| A level off the plot | If a level lies outside the strikes drawn, its badge is pinned to the edge with an arrow (on a phone the arrow follows its name in the key row), and it has no rule (a rule on the frame would sit on the outermost bar and name a strike it is not). Choose more strikes in Customise to bring it in. An example. |
| The strike rail | Strike labels under the bars. When the plot is narrow only some are printed, always including the strike nearest the price. |
| The value axis | On the right, headed GEX per 1% move, with round values such as ₹4000 Cr. The top of the axis is a round value, so the tallest bar always lands on a gridline. In the Gamma concentration view it starts at 0; in the others it is centred on 0. |
| The scope line | On a phone, one sentence under the legend: the expiry, the reading (latest reading, or as of a time when the replay is back), and the strikes drawn, for example All 81 strikes, 22500 – 26500 (or 11 of 81 strikes when you choose fewer). A desktop leaves the line out, because the choices are in Customise, and shows it only while the replay is on an earlier reading, with a Back to latest button beside it. |
The Readout
How do I read the exact figures for one strike, with a mouse, a finger or the keyboard?
Hold the pointer over a bar, or the empty space above and below it in the same column, and a card gives four figures for that strike: Call, Put, Net and Both sides. They are the figures of the formula in part A.
- With a mouse (desktop). The card follows the pointer, a little to its side. Near the right edge or the lower part of the plot it flips to the other side of the pointer so that it stays inside the plot. The bar under the pointer is highlighted.
- With a finger (phone or tablet). Tap a bar. The strike is pinned and the card stays in the corner of the plot, out from under the finger. Tap the same bar again to unpin it.
- With the keyboard. Each bar is a button that can be reached with Tab. When it has focus the card shows its strike; press Enter or Space to pin it, and the same key again to unpin it.
- Pinned strikes. A click on a bar pins it as well. A pinned card says pinned beside the strike and stays when the pointer leaves. Changing the symbol clears the pin; changing the expiry keeps it, so that you can look at the same strike on another expiry.
- A strike with no figure. The card says Not measured at this strike when no gamma could be worked out there (no usable price). The table at the foot of the page says Not measured in the same cells.
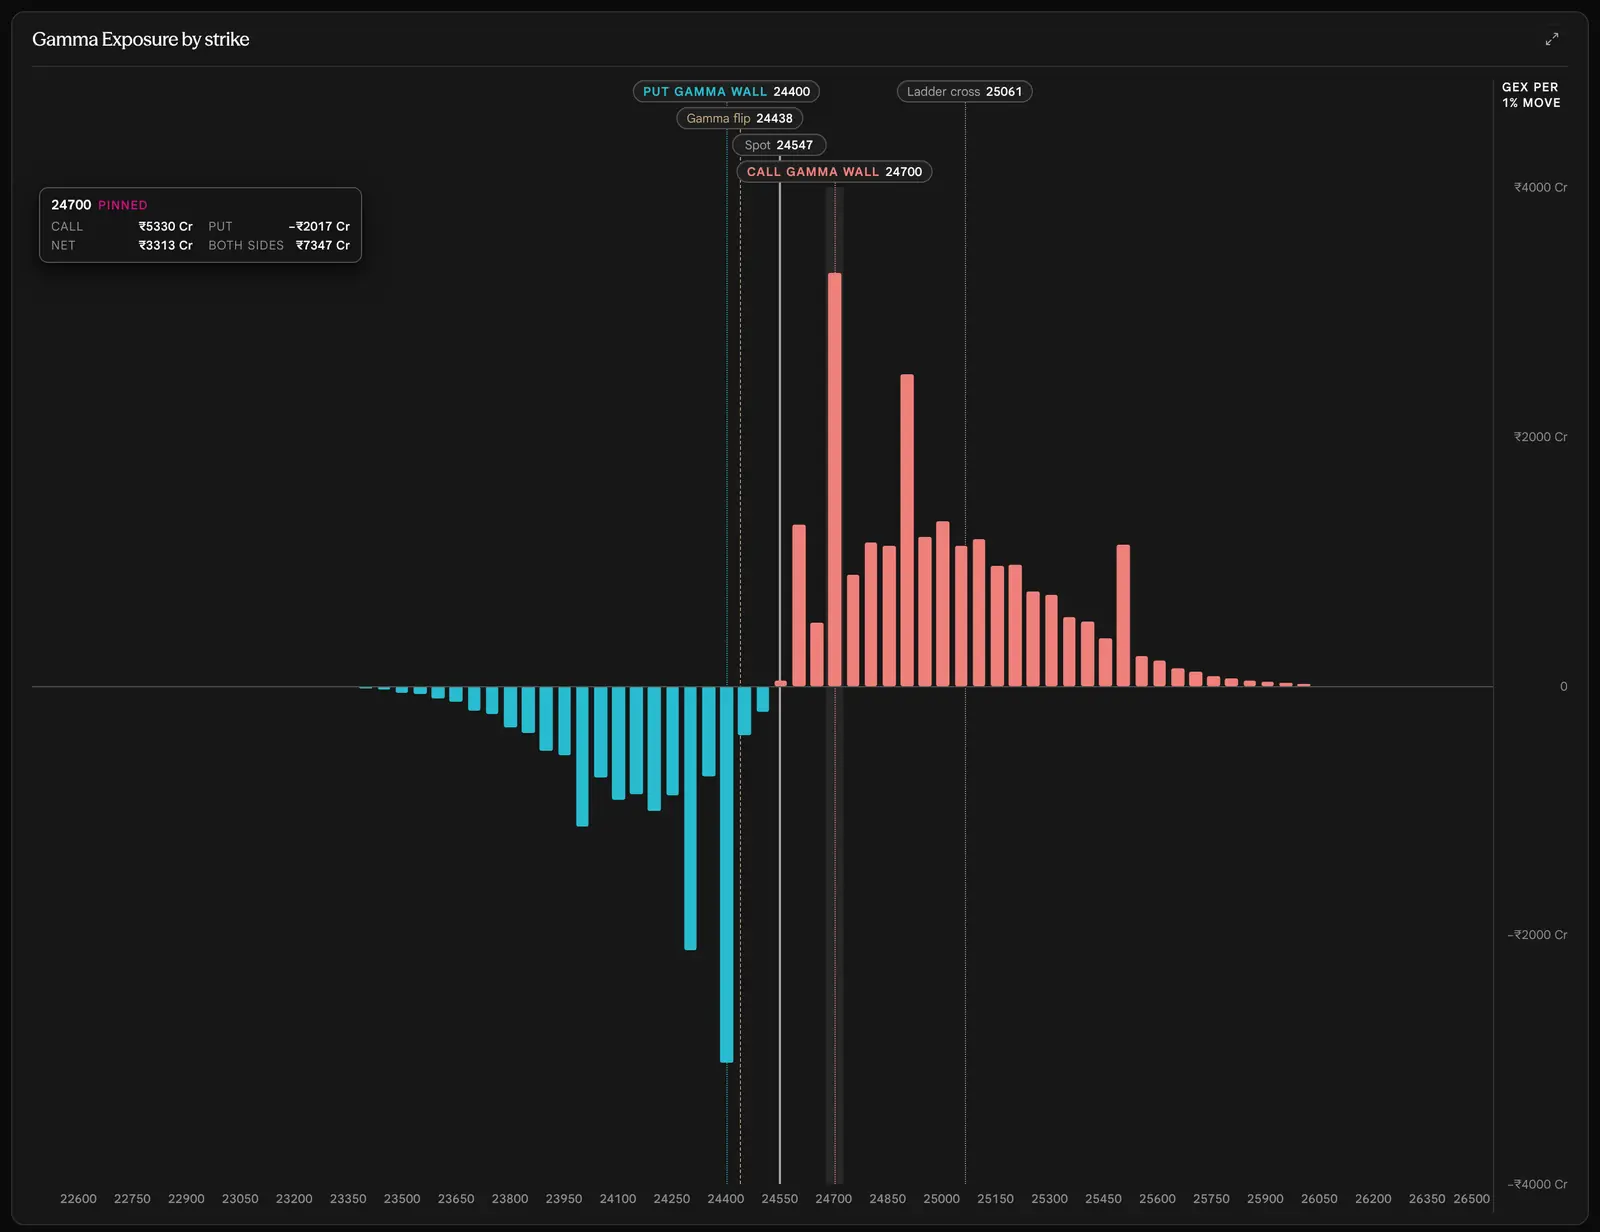
Where the Sign Changes: the Curve
What is the curve under the bars, and why is the flip read from it rather than from the bars?
The second card, Where the sign changes, answers a different question from the bars. The bars show the book at today's price. The curve shows what the total would be if the price stood at each level along the same strike axis: net gamma exposure recomputed at each candidate price, with the line crossing the zero rule at the gamma flip.


How the Curve Is Worked Out
Move the price
For each of about 120 candidate prices across the strikes drawn, the page pretends the underlying stands there.
Keep what was solved
Each strike keeps the volatility it was solved at. The forward moves in proportion to the price. The time to expiry is held fixed, because the question is where the flip is now, not where it will be tomorrow.
Recompute gamma and add up
Gamma at every strike is computed again at the candidate price and the Call-minus-Put sum is formed with the same formula. That gives one point of the curve.
The curve follows the strikes drawn: widening the strike count in Customise widens the curve too, which is also how you bring a flip that lies outside the plot into view. The page then says so in the line under the curve. The curve always shows the flip and the price, whatever the Levels switches in Customise say.
The Levels: Gamma Flip, Ladder Cross, Walls
What are the gamma flip, the ladder cross, the gamma walls and the heaviest strike, and how is each found?
| Level | The question it answers | How it is found | In the pictures |
|---|---|---|---|
| Gamma flip | At what price would the whole book's Net change sign? | Solved: the book is re-priced at candidate prices and the sign change is narrowed down. Not read off the bars. | 24438, 109 points below the price |
| Ladder cross | At what strike does the running total of Net, added from the lowest strike up, cross zero? | Interpolated between the two strikes where the running total changes sign. Printed only if it crosses. | 25061 |
| Call gamma wall | Above the price, where is the Call side's hedging thickest? | The strike above the price with the largest Call GEX. | 24700 |
| Put gamma wall | Below the price, where is the Put side's hedging thickest? | The strike below the price with the largest Put GEX (by size). | 24400 |
| Heaviest strike | Where is the most gamma, either side of the price? | The strike with the largest Both sides figure. Marked Heaviest strike in the table. | 24700 |
The Gamma Flip: Solved, Not Interpolated
There is a cheap way to find a level where the total changes sign: add the strikes up from the lowest and look for the strike where the running total crosses zero. The page does that, and calls the result the ladder cross, but it does not call it the flip. The running total is a display device; it does not ask what the book would be if the price were somewhere else. The flip does. The page re-prices the whole ladder at candidate prices from 25% below the price to 25% above it (400 steps), finds each place where the sign changes, and narrows each one down by repeated halving. If there is more than one crossing it uses the one nearest the price.
The two answers are different questions and can be far apart. In the pictures the flip is 24438 and the ladder cross is 25061, 623 points apart. The page therefore flags both, on the chart and in the detail panel, and the first caution list says the ladder cross is a different level from the flip. The flip is sometimes called the zero-gamma level elsewhere (what we have not verified); this page calls it the gamma flip.
- No flip in range. If the total never changes sign within 25% of the price, the Flip chip is left out, the row says No flip within 25% of NIFTY, and the box says the modelled hedging leans against or runs with every move across that whole range.
- The flip is a modelled level. It moves when the Open Interest, the prices or the time to expiry move. It is not a price that must hold.
- On the chart the flip is drawn as a dashed rule with a badge (on a phone, with its name in the key row); if it is outside the strikes drawn, the badge is pinned to the edge with an arrow.


The Walls
The page labels them Call gamma wall and Put gamma wall. A gamma wall names a strike that the price would have to travel to. For that reason the page looks for the Call gamma wall only above the price and the Put gamma wall only below it. An unrestricted search would put both walls on the at-the-money strike, where gamma is highest on both sides at once. The Call gamma wall is the strike above the price with the largest Call GEX; the Put gamma wall is the strike below it with the largest Put GEX by size. Strikes with no usable gamma are skipped. It is where the modelled book is thick, not a price that must hold. If no strike qualifies, the badge is left out.
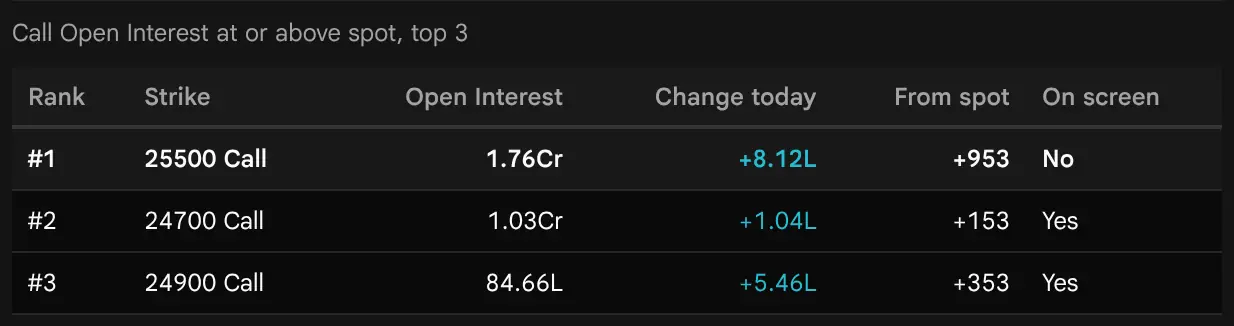
Gamma walls are not Open Interest walls. The Option Chain, the Open Interest page and the detail panel here also show walls that are the strikes with the most Open Interest on each side, and they can be a different strike, because gamma falls away with distance from the price. In the pictures the Call gamma wall is 24700 but the Call wall by Open Interest is 25500. Part D works this through.


The Session Cards and the Replay
What do the three session cards show, when do they appear, and how does the replay move everything?
Below the curve, up to three more cards show how the day has gone. They need two or more readings from the session, so they do not appear when the page has only one (the states). A session is one trading day: the page uses the latest date in the archive and never mixes days. All three cards draw on one clock axis from 9:15 to the derivatives close, so a point in the same column of each card is the same moment.

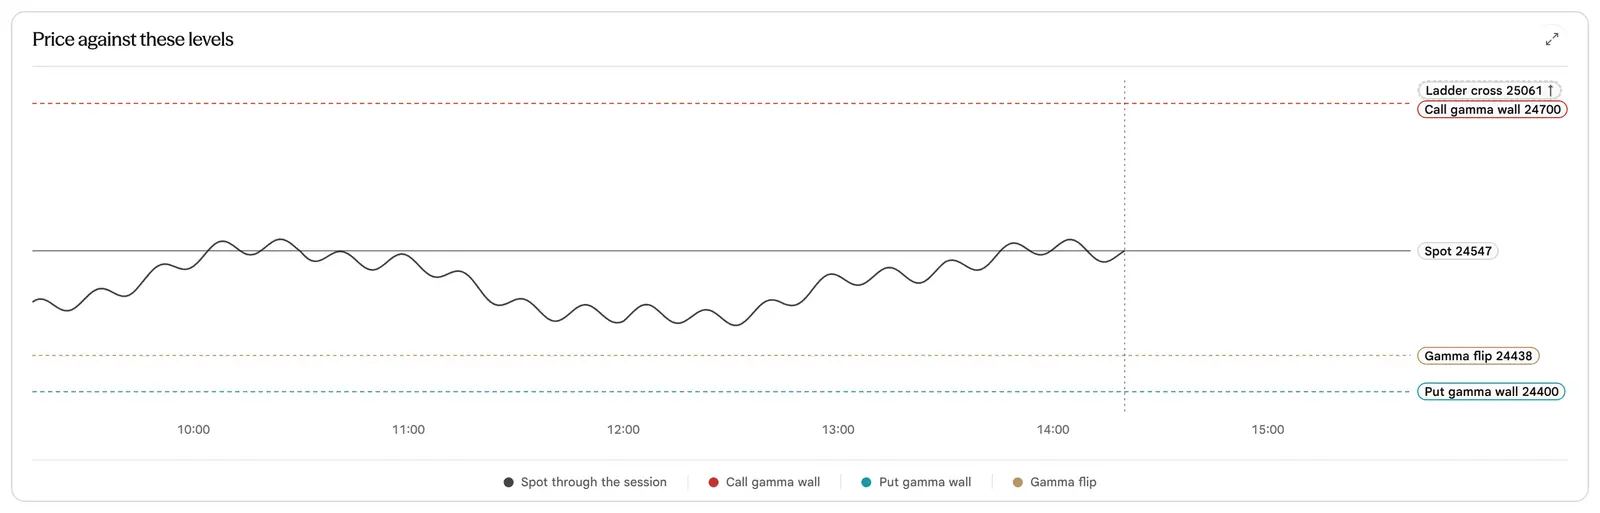
The line is a plain line rather than candles because the archive keeps one price a minute: there is no high or low to draw, and a candle built from one price would be mostly invention (the page's own note).
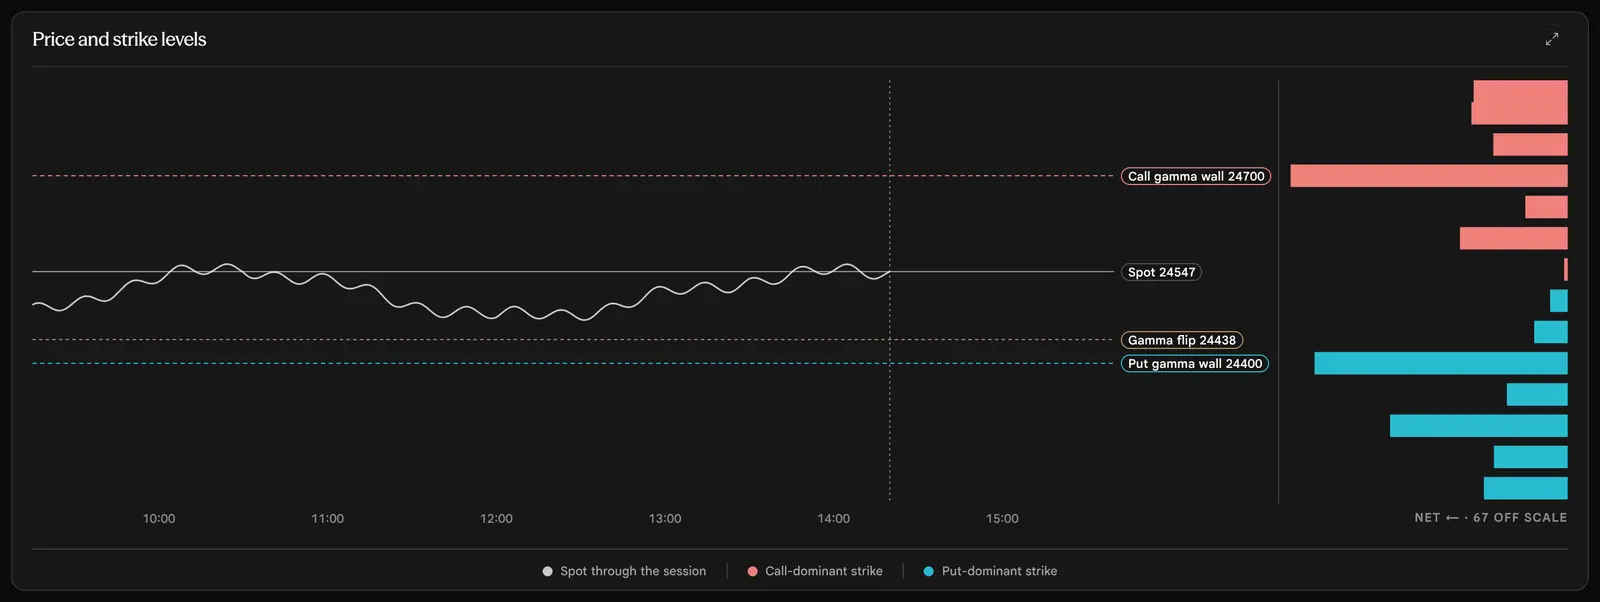
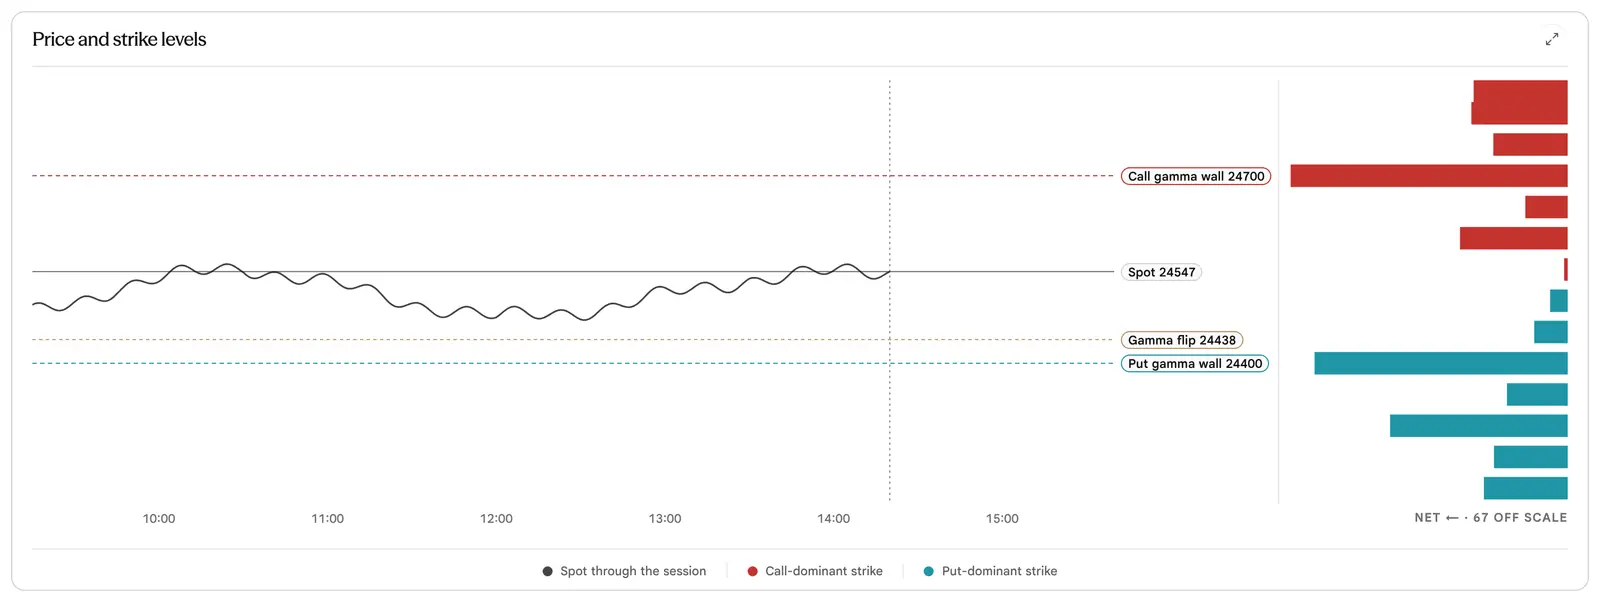
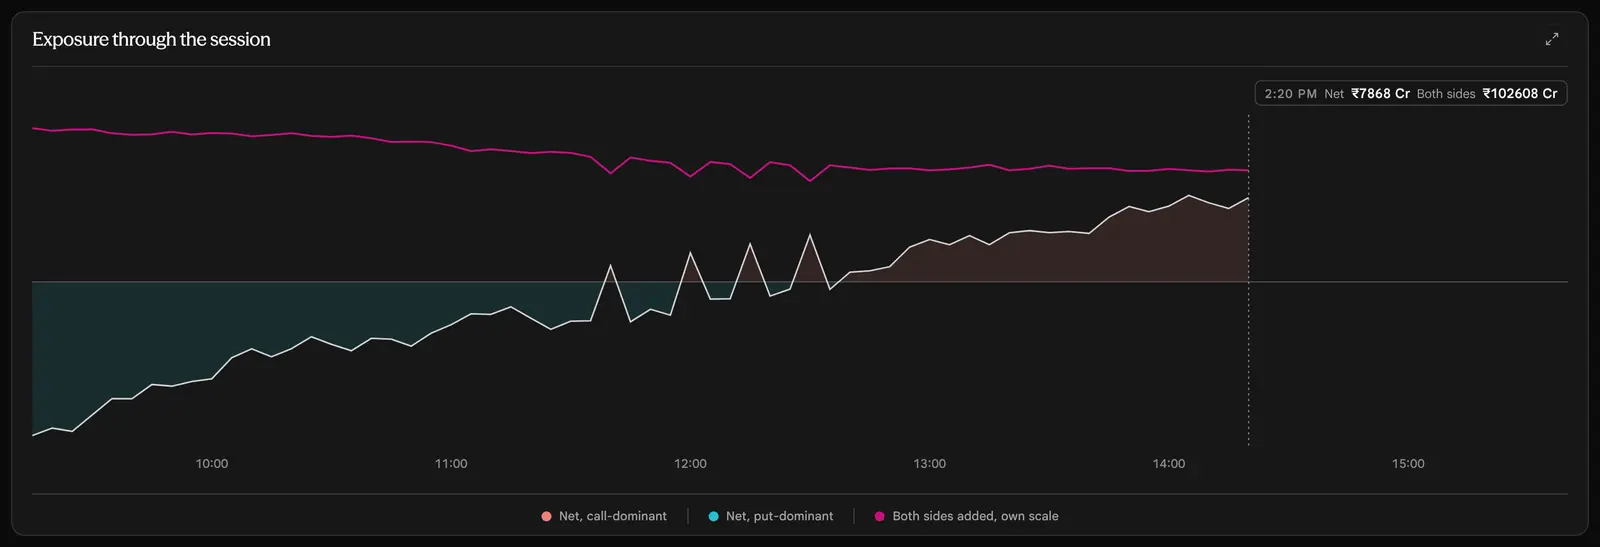
- One reading in five minutes. The series card uses one reading in each 5 minutes (at most 120 points), and re-solves the volatility from traded prices at each one, because the archive keeps no Greeks.
- A growing ladder. If the ladder gained strikes during the window, the card says so: part of any rise is the book being listed, not positions being taken.
Session Replay
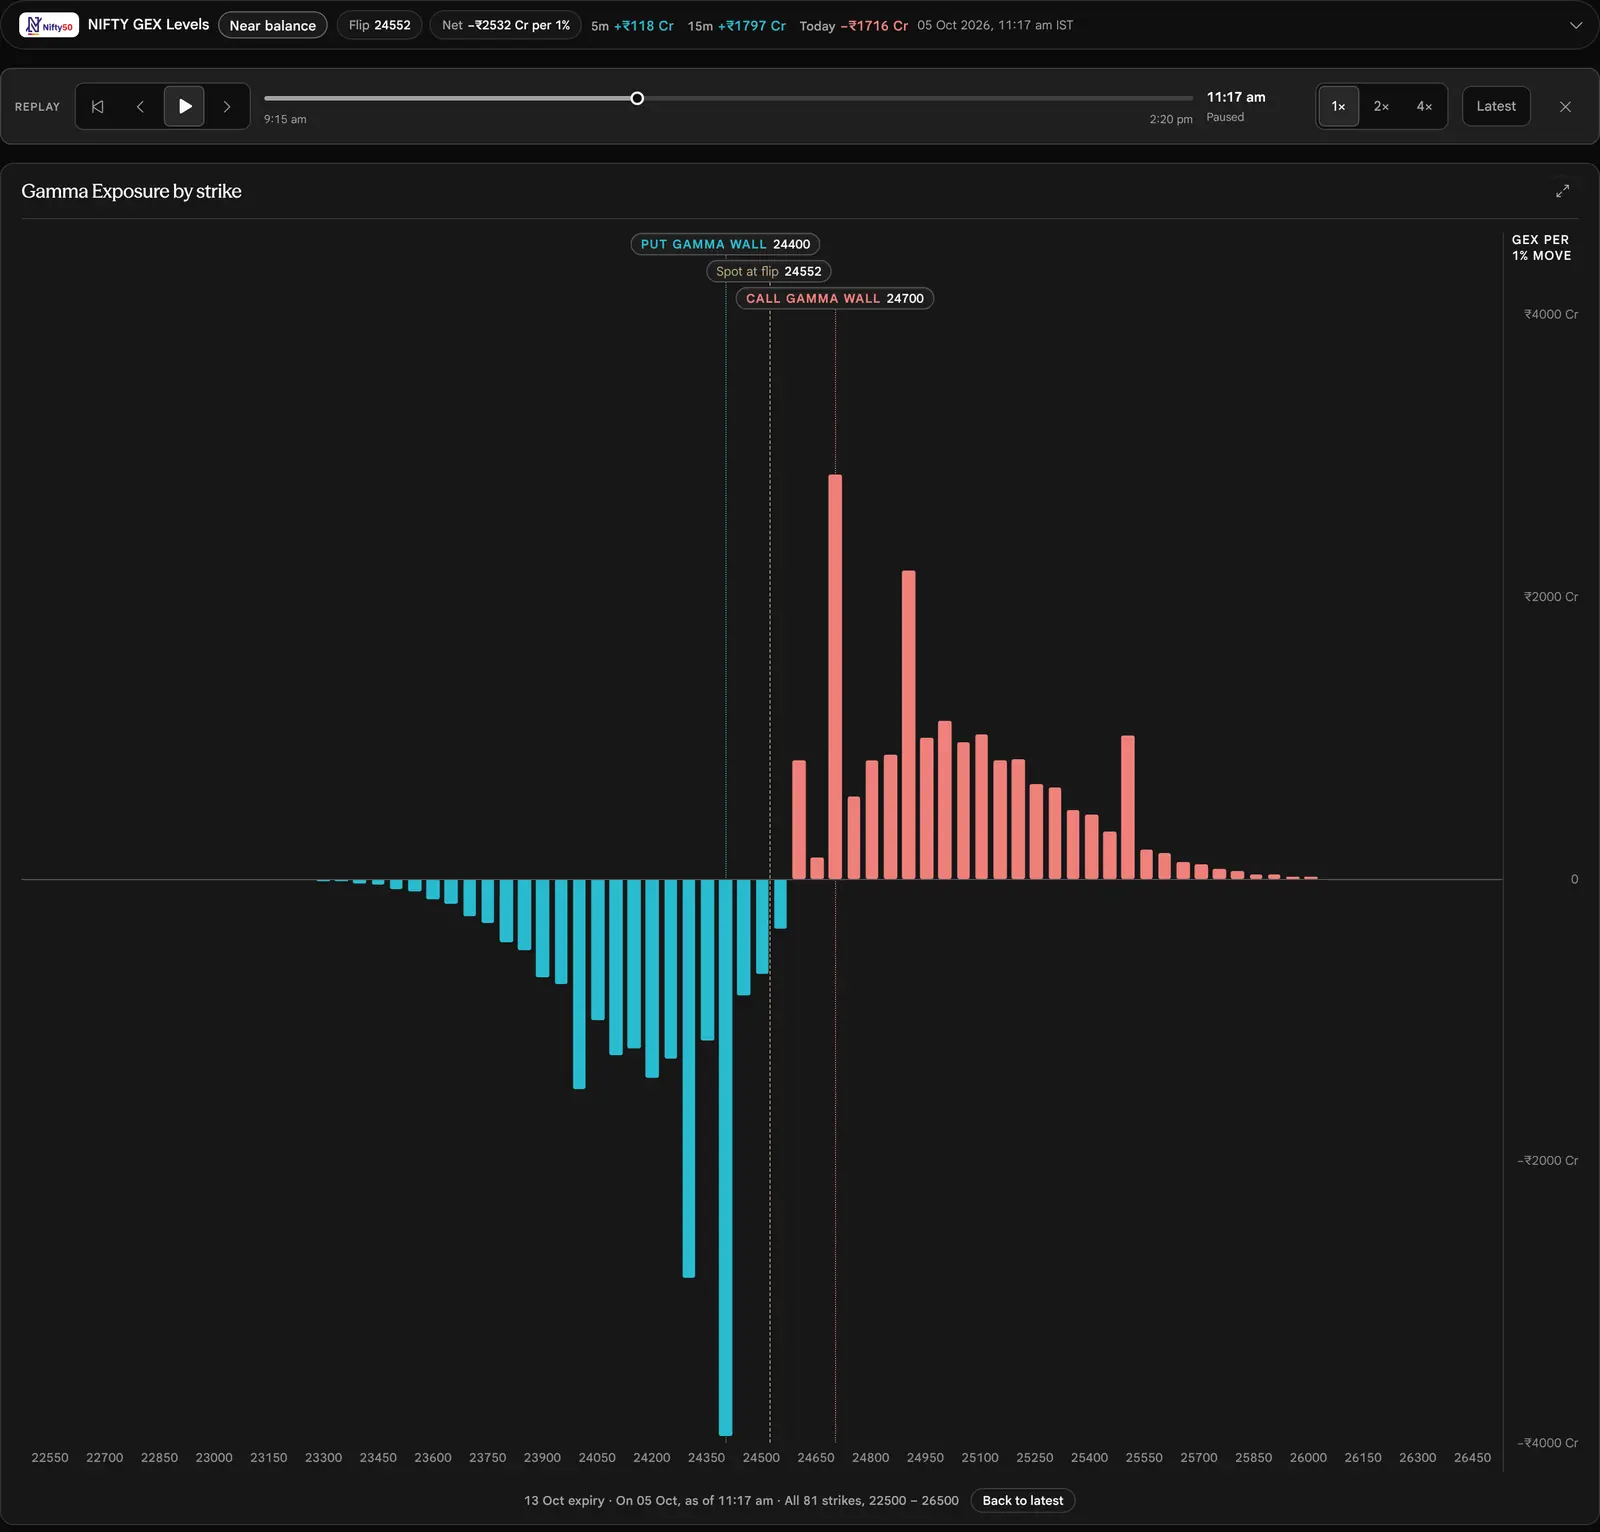
Open Customise, then Time, and switch Session replay on. A strip opens above the cards with a scrubber from the first reading to the latest, buttons to step and play, the speeds 1×, 2× and 4×, Latest and a close button. Every chart and figure on the page follows the scrubber: the insight row and box, the bars, the badges, the curve and the table. The three-window changes (5m, 15m, Today) are measured from the reading you have scrubbed to, and the scope line says as of that time. The switch is dimmed with a line of explanation when the session has fewer than two readings. The replay is never remembered, and it closes when you change the symbol or the expiry.
Every Strike: the Table
Where do I find every figure in words and numbers, for the whole ladder?
The last card, Every strike, restates the profile as a table. Nothing on the page exists only as a mark. It holds the whole ladder, not only the strikes drawn, because the chart is a view and the table is the record. It opens on Key levels: the strike nearest the price, the strike nearest the gamma flip, the two gamma walls and the heaviest strike. The All strikes capsule beside it lists every strike, and Find strike filters by number.


| Column | Meaning |
|---|---|
| Strike | The strike price, lowest first, with its marks (below) under it. |
| Call | Call GEX: never negative. |
| Put | Put GEX: never positive, printed with a true minus sign. |
| Net | Call plus Put. |
| Both sides | Call plus the size of Put: no holder assumed. |
| Marks | Nearest spot, Nearest flip, Call gamma wall, Put gamma wall or Heaviest strike where the strike is one of those; otherwise empty. A strike that earns more than one mark shows all of them, stacked in that order. These are the gamma walls: the Open Interest walls (Call wall, Put wall) are a different pair, shown in the insight. |
Every figure is in rupees per one per cent move, printed as ₹5330 Cr for a crore or more, ₹1.5 L for a lakh, and < ₹1 L when a strike's figure is too small to matter. A strike with no usable price prints Not measured in each cell.
The question each topic answers (4 topics)
The Insight Row
What is each piece of the one-row summary at the top of the page?


| Piece | What it says | When it is missing |
|---|---|---|
| Verdict pill | One of Hedging dampens moves, Hedging amplifies moves, Near balance or Not measured. How it is decided. | Never missing. |
| Flip chip | The gamma flip: 24438. | Left out when the book is not measured or no flip lies within 25% of the price. |
| Net chip | The total, ₹7868 Cr per 1%: rupees of hedging per one per cent move. | Left out when the book is not measured. |
| 5m, 15m, Today | How far Net has changed: now minus the reading about five minutes back, fifteen minutes back, and the previous session's close. Green marks a rise in Net and red a fall. The colour is the direction of the change in Net, not a verdict on it. | A dash, with the reason in words for a screen reader (for example This is the session's first reading, so the 5-minute window has no baseline yet). A dash is not zero. |
| The gist | One line: how far the price is from the flip, for example NIFTY 109 above the flip, followed by the expiry when there is room. | Steps out when the row is too narrow to print it whole. With no flip in range it reads No flip within 25% of NIFTY. |
| The stamp | The time of the reading the page is showing, in India time, for example 05 Oct 2026, 02:20 pm IST. | Never missing. |
| The arrow at the right end | Opens the box (next). A screen reader names it Show the full insight. On a phone the box opens as a sheet. | Never missing. |
Today is measured against the previous session's close of the same expiry, when the archive holds it. When it does not, the page uses the first reading of this session and says so in the box (“since 9:15 am”), never silently. The 5m and 15m figures need an earlier reading close enough to five or fifteen minutes back (the exact tolerance is not stated in this guide).
The Insight Box
What do the reason, Measured over, the four sentences and the cautions say?
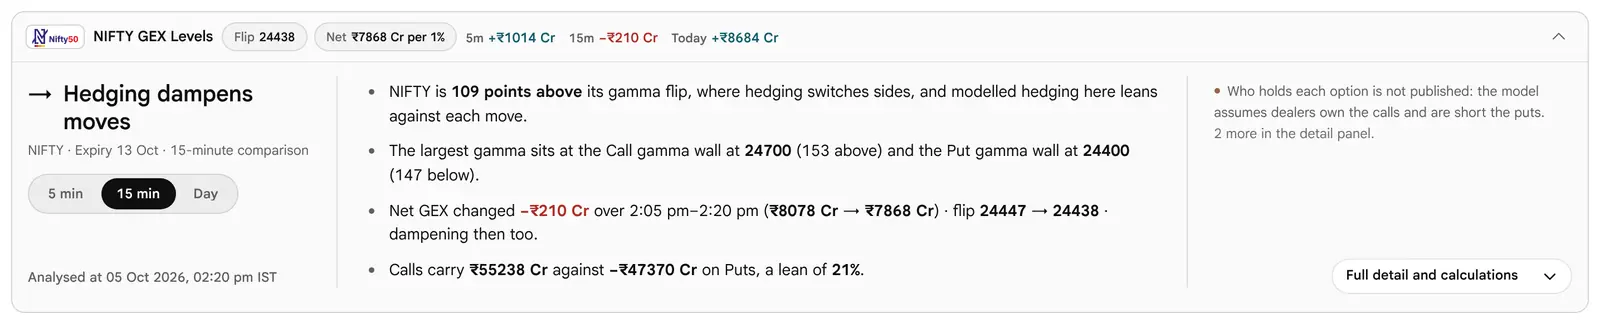
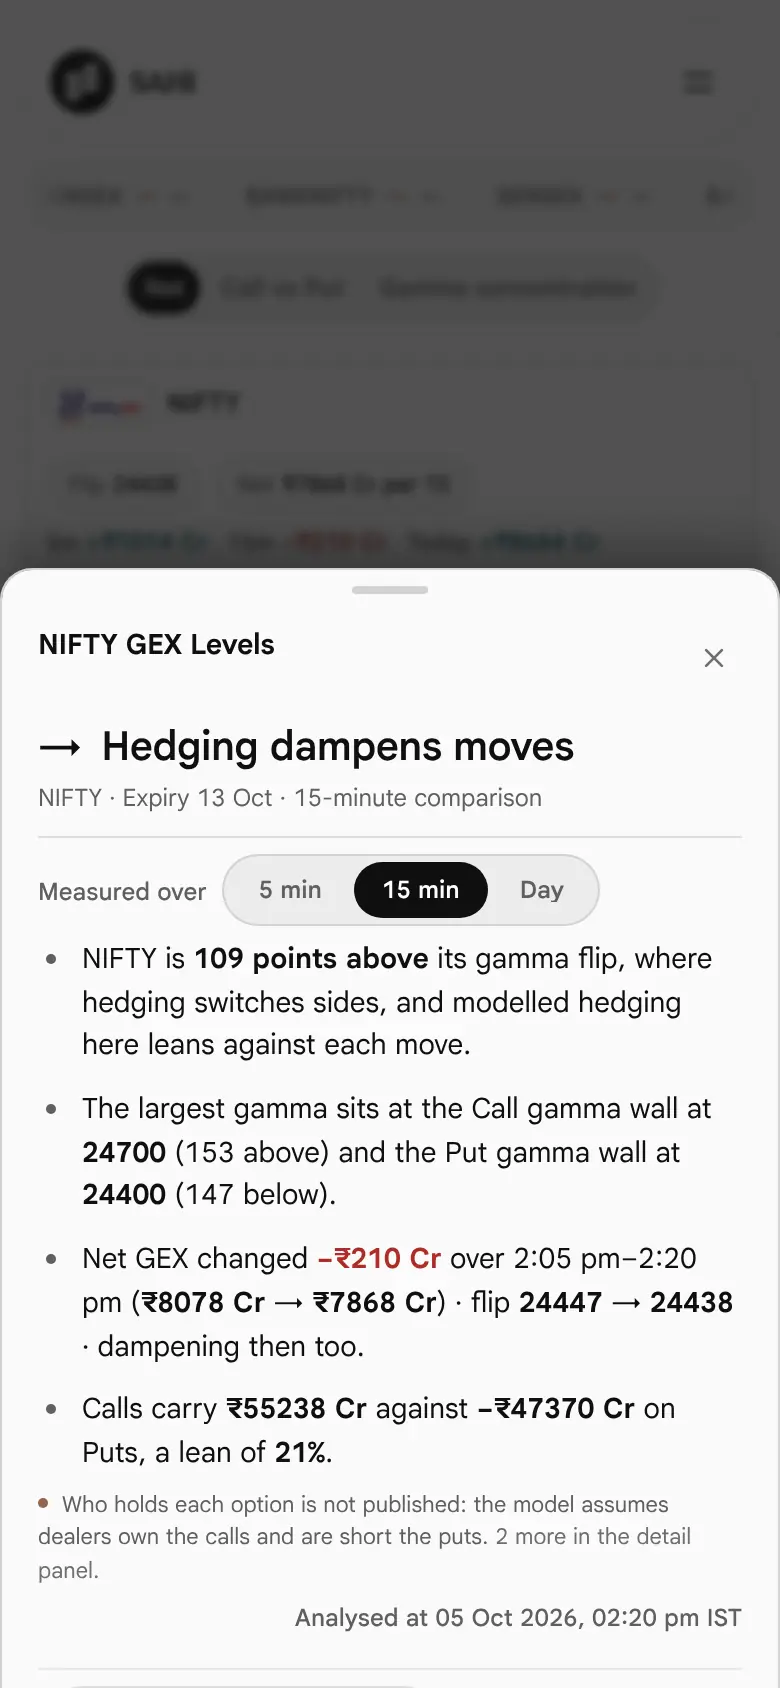
Press the arrow at the right end of the row and it opens into a box. On the left it repeats the verdict with its context (NIFTY · Expiry 13 Oct · 15-minute comparison) and the Measured over capsule. In the middle are four bulleted sentences, and at the right the first caution. The first sentence is the reason: in the pictures it says NIFTY at 24547 is 109 points above its gamma flip 24438 (where hedging switches sides), and modelled hedging here leans against each move.

The Four Sentences
| Sentence | What it says | In the pictures |
|---|---|---|
| The flip | How far the price is from the gamma flip, and what that means for hedging. A standing level: it does not depend on Measured over. | NIFTY is 109 points above its gamma flip, and modelled hedging leans against each move |
| The levels | The Call gamma wall and the Put gamma wall with their distance from the price, from highest to lowest. | Call gamma wall 24700 (153 above) · Put gamma wall 24400 (147 below) |
| The change | How far Net moved over the window you chose, with both ends, the flip then and now, and whether the book was in the same regime then. | Net −₹210 Cr over 2:05 pm–2:20 pm (₹8078 Cr → ₹7868 Cr) · flip 24447 → 24438 · dampening then too |
| The book | The Calls and Puts Net is made of, and the lean. It is a standing level too. | Calls carry ₹55238 Cr against −₹47370 Cr on Puts, a lean of 21% |
Measured Over
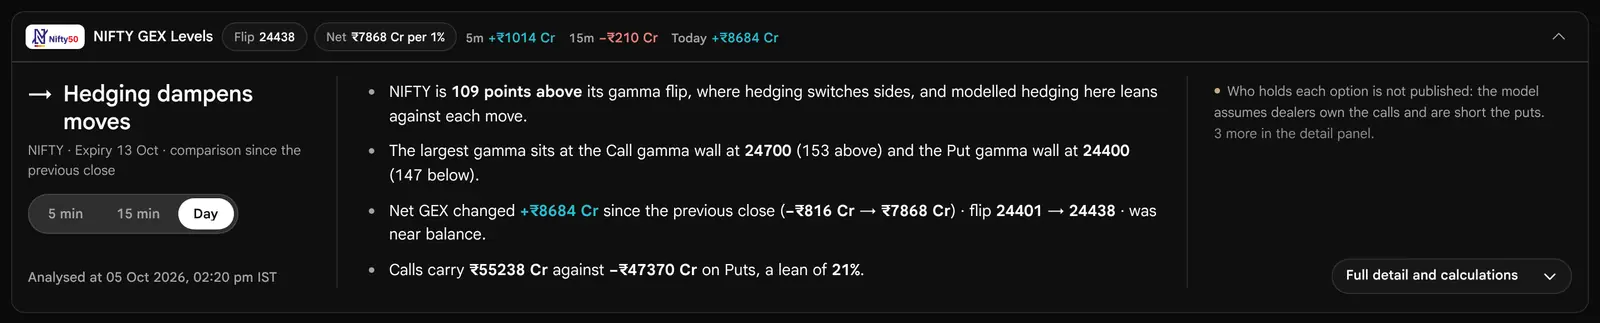
The capsule Measured over offers 5 min, 15 min and Day. It sets the change sentence and nothing else: the verdict, the flip, the levels and the book do not move. The page opens on 15 min for an index and on Day for a stock, and remembers your choice for this page and this kind of instrument. A window with no earlier reading to compare with is dimmed, and the reason is given. Day compares with the previous session's close.

Cautions
The box prints the first caution and says how many more the detail panel holds. They are, most important first: who holds each option is not published; the page reads this one expiry alone, so hedges carried in other expiries are not seen; the ladder cross is a different level from the flip; if no forward could be formed, gamma was solved on the price, which on the real ladders checked made Net 55 to 65% smaller, and every other figure moves as well; if Open Interest does not look like whole lots, rupee totals may be scaled wrongly (the flip and walls are unaffected); the share of Open Interest left out when some strikes have no gamma; a growing ladder; and, on Day, that gamma grows as expiry nears so part of a change across sessions comes from the calendar rather than from positions.
The Detail Panel
How is every figure worked out, and where do I check it?
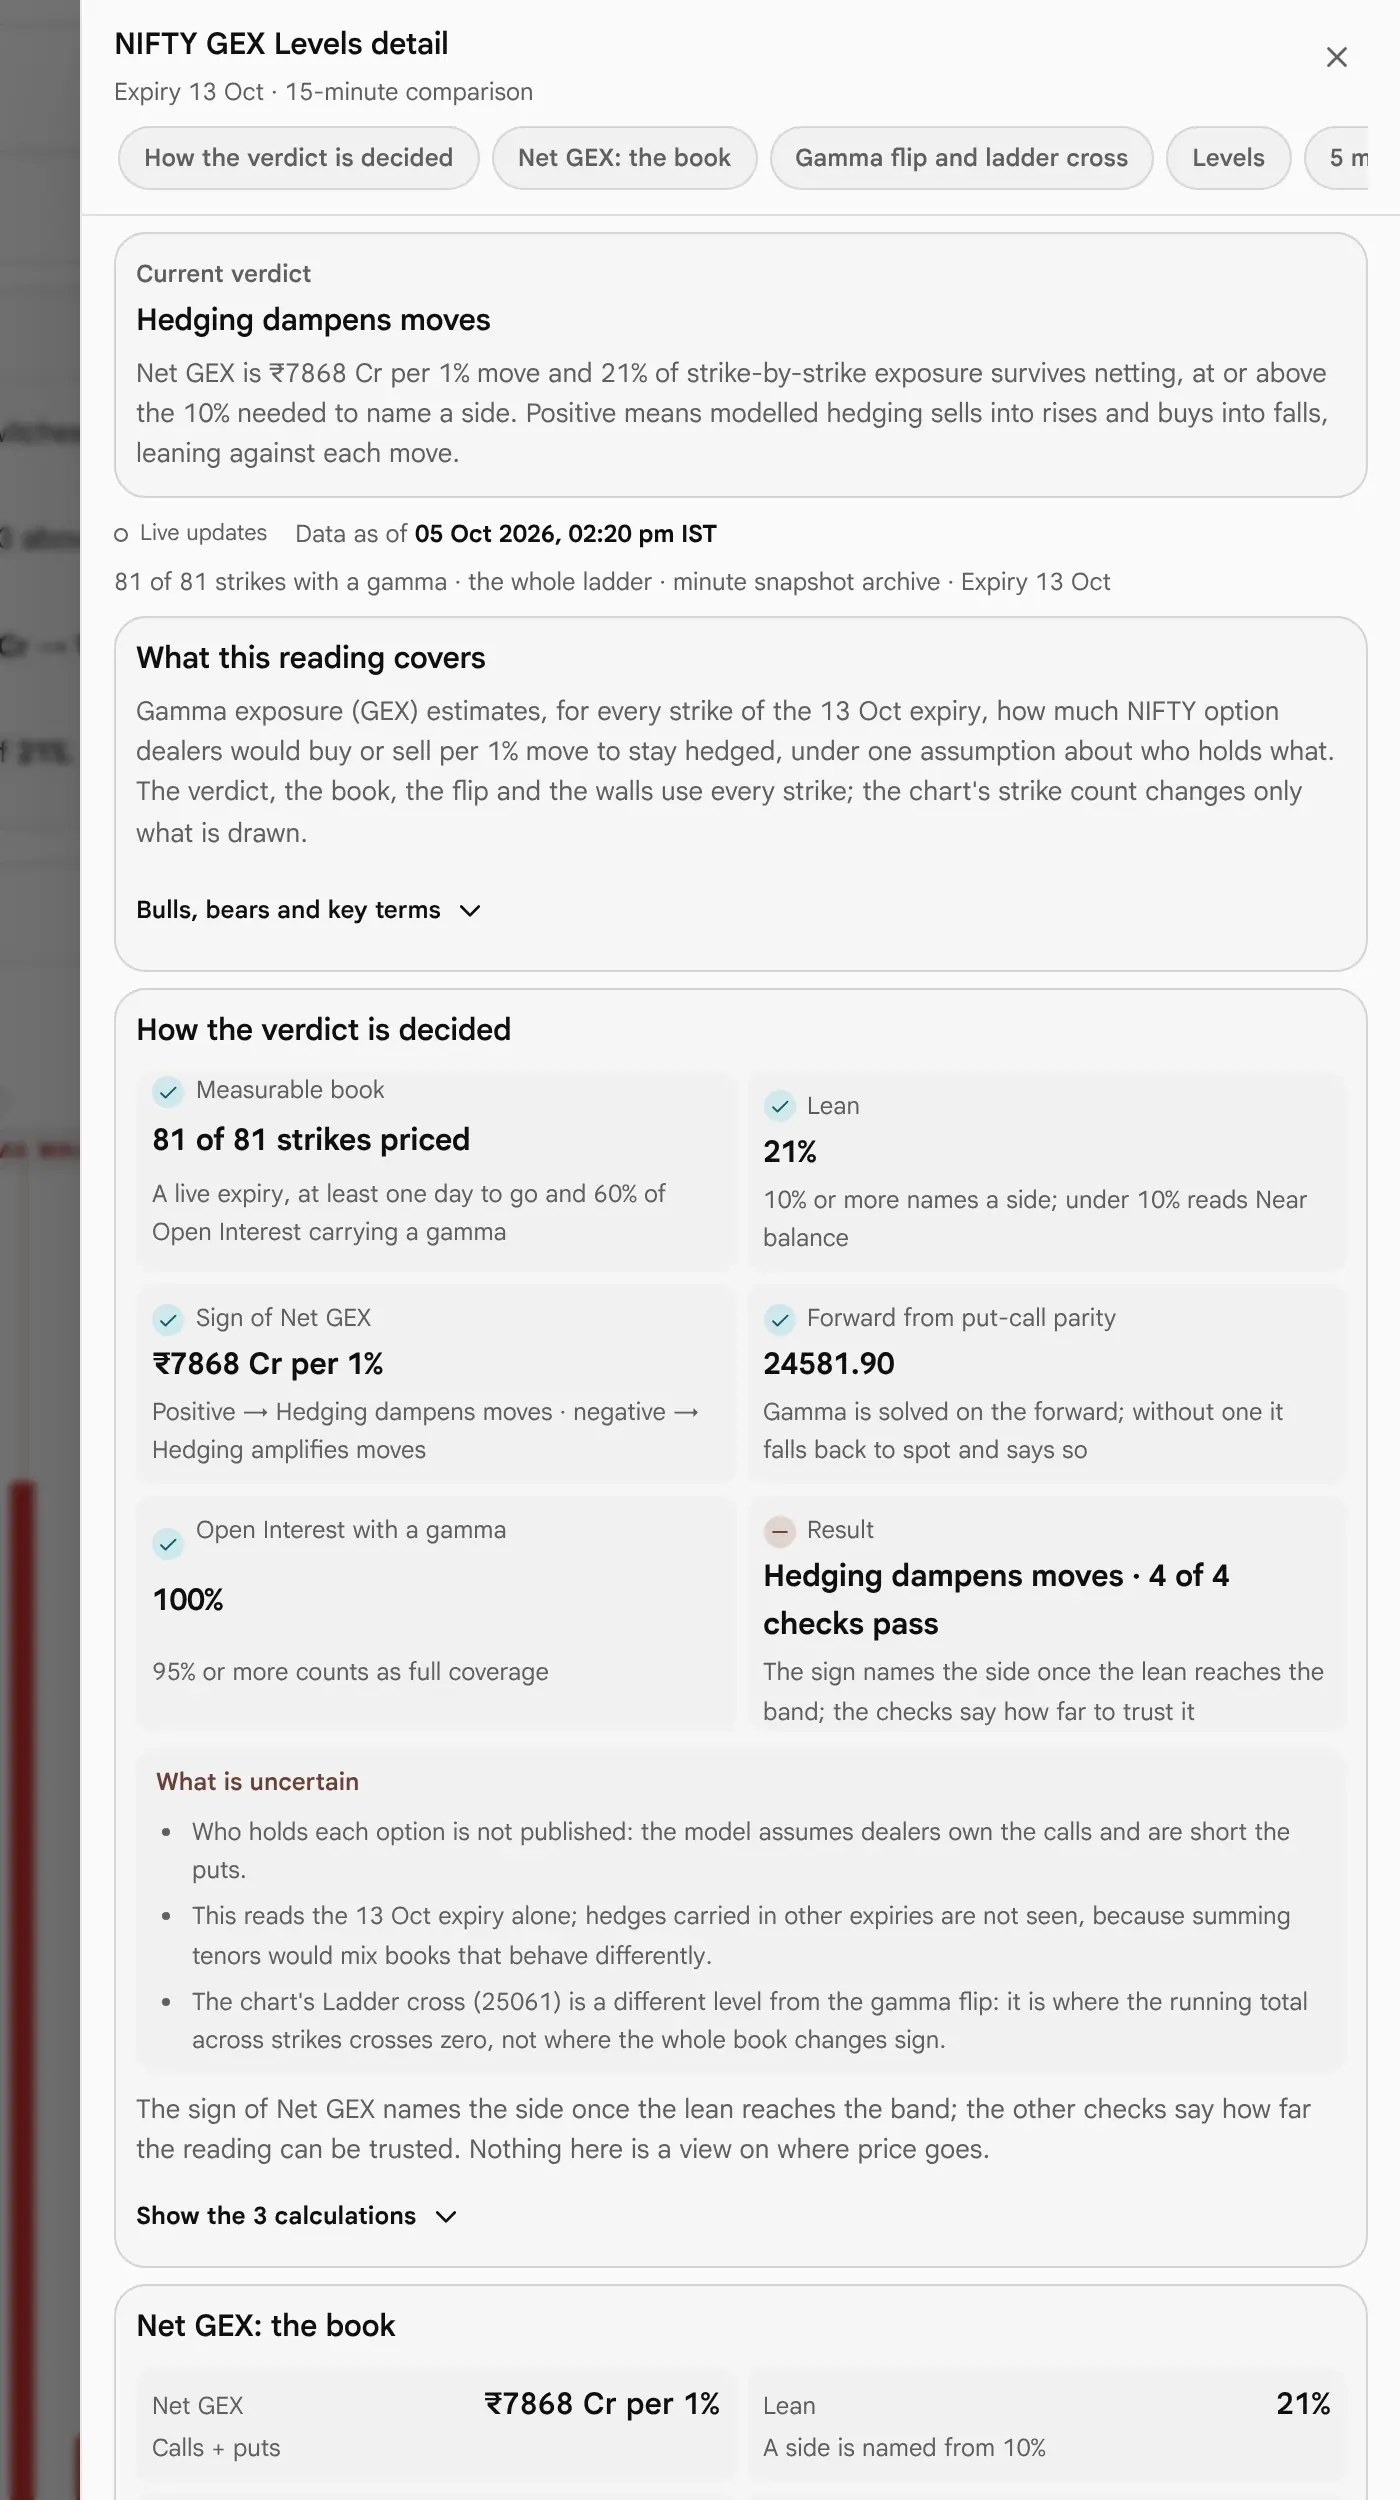
Press Full detail and calculations in the box. A panel opens at the right of the page (a full sheet on a phone) with a strip of links to its sections. Every figure in the row and the box is printed from one place, so the row, the box and the panel can never show two versions of one number. Each section ends with a fold, Show the N calculations, that unfolds the arithmetic.

| Section | What it holds | Where in this guide |
|---|---|---|
| Current verdict, What this reading covers | The verdict with a plain-words reason, and what the reading includes. | Verdict words |
| How the verdict is decided | Five lines, each with its rule and value (a measurable book, the lean, the sign of Net, the forward, the share of Open Interest with a gamma) and a Result line that counts how many of four checks pass (measurable, forward, coverage, lean). Then What is uncertain. | Where gamma comes from |
| Net GEX: the book | Net, Calls, Puts, Both sides, the lean and the heaviest strike, and a table of the 21 strikes nearest the price with Gamma, Call Open Interest, Put Open Interest, Call GEX, Put GEX and Net. Show all N rows lists every strike. | The formula |
| Gamma flip and ladder cross | The two levels, the scan range and what each is. | The levels |
| Levels | Call wall (Open Interest), ladder cross, Call gamma wall, heaviest strike, the price, flip and Put gamma wall, with distance from the price. | Gamma walls and Open Interest walls |
| 5 min, 15 min and Today | The change of Net over each window with the two readings and the arithmetic, and the snapshots matched. | The row |
| Data and scope | One expiry, every listed strike, the reading's time, and a glossary of the page's terms. | Glossary |


What the Page Says When It Has Nothing, or Little
What does the page say when it is loading, has one reading, cannot measure the book, or fails?
The page prefers a sentence to a blank or a guess. A dash is never a zero, and a withheld figure always comes with its reason.
| State | What you see | What it means |
|---|---|---|
| Loading | The profile card says Loading the ladder… | The first reading has not arrived. |
| One reading only | The profile and the curve are drawn; the 5m, 15m and Today figures are dashes with their reasons; the three session cards and the replay switch are missing or dimmed. | There is no minute archive for the session, so the page works from the current chain alone (where the data comes from). |
| Not measured | The verdict reads Not measured, there are no chips, and the card gives a sentence naming the cause. | Expiry day, a settled series, thin coverage, no usable price or no Open Interest (the list). |
| Error | A notice at the top, Gamma Exposure could not be loaded, with the message, and the card says it is not available. | The backend did not answer, or there was no expiry to read. |




The question each topic answers (9 topics)
- What can I change, what are the defaults, and what is remembered?
- What do these readings look like with figures, and what can each support?
- How are gamma walls different from Open Interest walls, and how does this page relate to the Option Chain, Open Interest and PCR?
- How do I use the page before the open, in the session, on expiry day and positionally?
- What do readers get wrong, and what should I check before I act?
- Where do the readings come from, how old are they, and what is not on the page?
- When should I use this page and when another?
- How do I use the page, and this guide, on a phone?
- What does the page not do?
Customise: What You Can Change
What can I change, what are the defaults, and what is remembered?
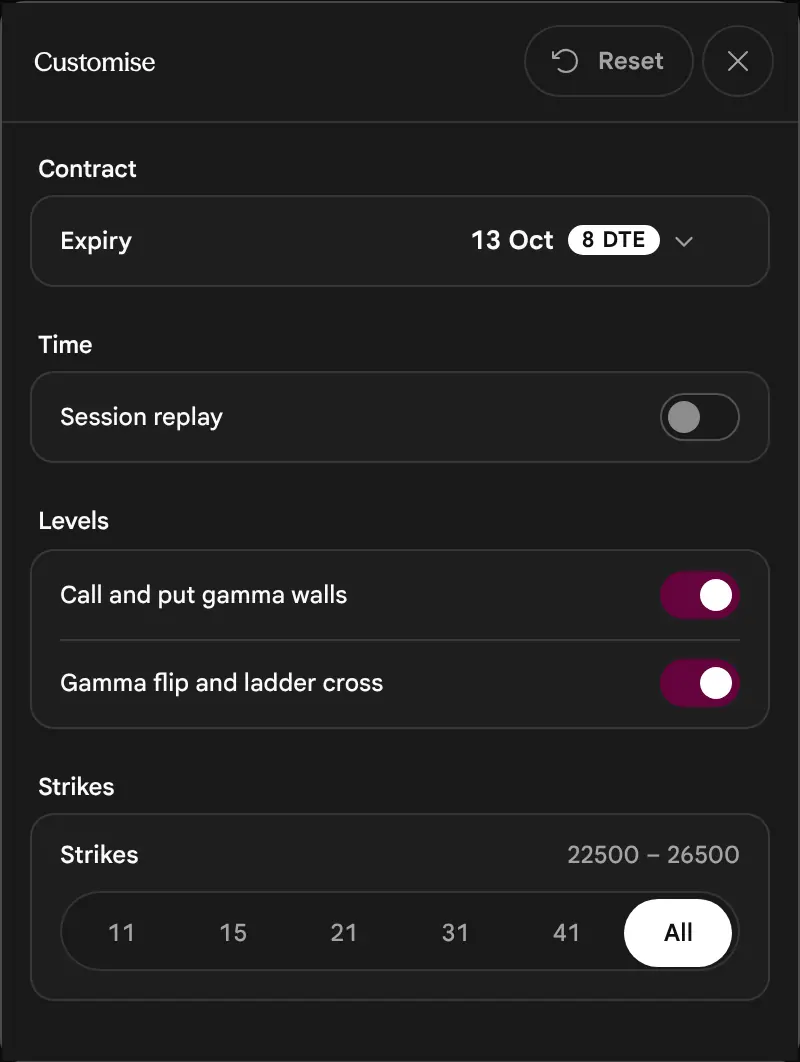
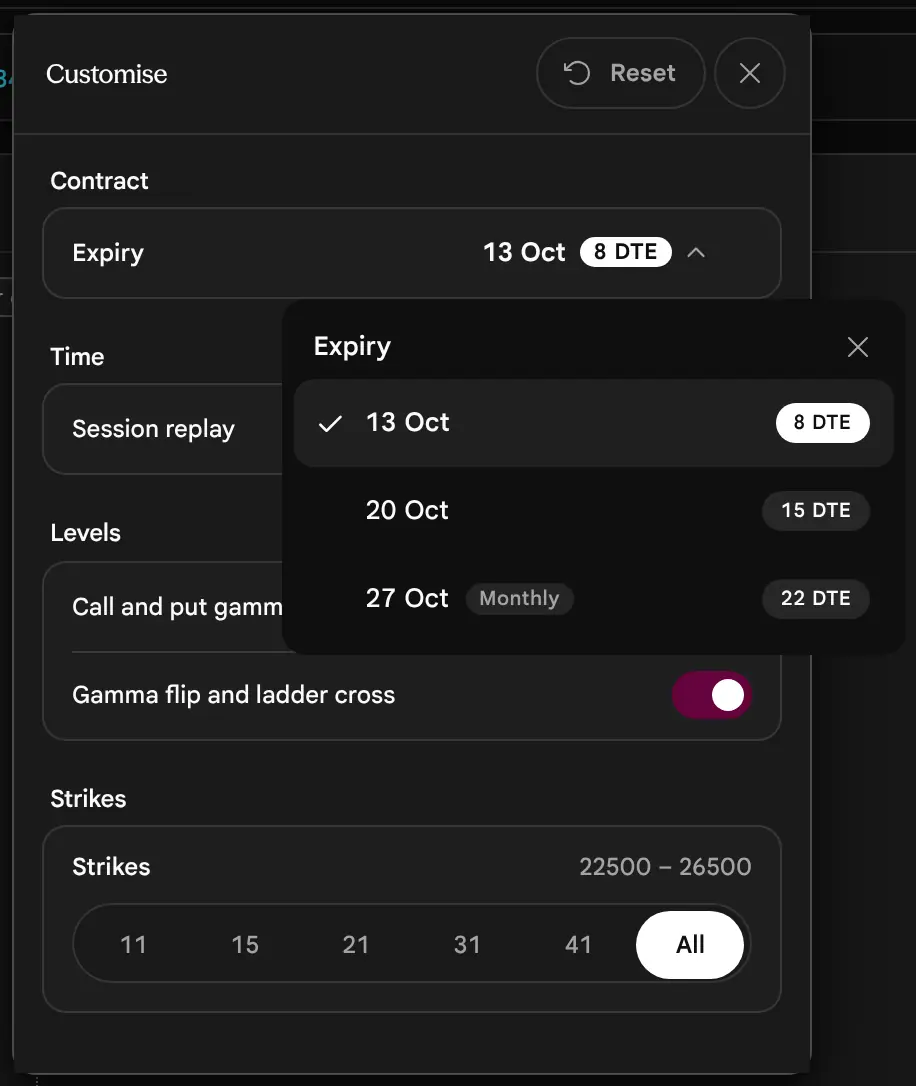
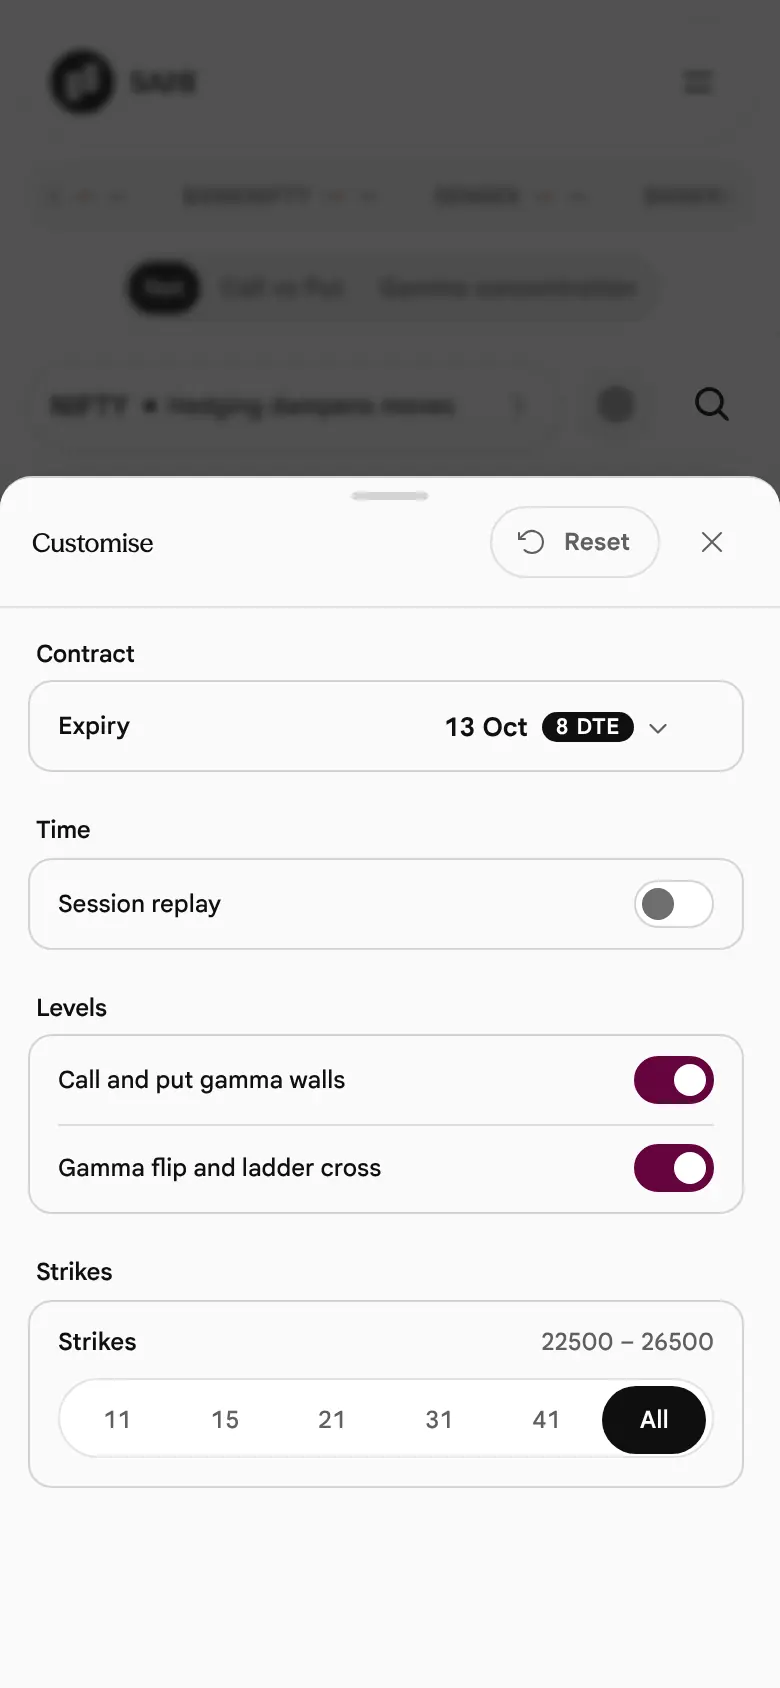
Press Customise on the page bar. A panel opens under the button with four sections. Every change applies at once, so the only buttons are Reset and Close. Escape closes the panel and returns focus to the button. The plot view is not in the panel: it is the capsule on the page bar.





| Control | Choices | Default | Remembered in this browser? |
|---|---|---|---|
| Plot view (page bar) | Net, Call vs Put, Gamma concentration | Net | Yes (gexView:v1) |
| Expiry (Contract) | The expiries the chain lists, with days to go | The nearest | No. Reset leaves it alone: it is the contract being read, not a preference. |
| Session replay (Time) | Off or on (needs two readings) | Off | Never |
| Call and put gamma walls (Levels) | On or off | On | Yes (gexCustomise:v1) |
| Gamma flip and ladder cross (Levels) | On or off | On | Yes |
| Strikes | 11, 15, 21, 31, 41, All | All strikes, on a desktop and on a phone | Only a count you chose is kept, so a phone and a desktop each open on All until you choose. |
| Measured over (insight box) | 5 min, 15 min, Day | 15 min for an index, Day for a stock | Yes, per page and kind of instrument |
Strikes and Levels in Pictures
An index ladder can run past a hundred rungs. The page opens on the whole ladder, because a wall or the flip can sit far from the money and only the whole ladder shows them all. All is the default. Choose a smaller count in Customise when the bars sit too close together to read.




Worked Examples (Illustrative)
What do these readings look like with figures, and what can each support?
Example 1: One Day That Changes Regime
In the invented book the Puts are ahead at the open, the two sides level off through the morning, and the Calls move ahead in the afternoon. The page's model reads that day at six moments:
| Time | NIFTY | Verdict | Lean | Net per 1% | Gamma flip | Flip against the price |
|---|---|---|---|---|---|---|
| 9:20 am | 24493 | Hedging amplifies moves | 31% | −₹13654 Cr | 24652 | 159 above the price |
| 10:30 am | 24546 | Hedging amplifies moves | 14% | −₹5830 Cr | 24615 | 69 above the price |
| 11:30 am | 24496 | Near balance | 9.3% | −₹3675 Cr | 24543 | 47 above the price |
| 12:30 pm | 24470 | Hedging dampens moves | 13% | ₹4373 Cr | 24406 | 64 below the price |
| 1:30 pm | 24535 | Hedging dampens moves | 12% | ₹4597 Cr | 24473 | 62 below the price |
| 2:20 pm | 24547 | Hedging dampens moves | 21% | ₹7868 Cr | 24438 | 109 below the price |
- 9:20 am. Put exposure outweighs Call exposure and the lean is far above 10%. The verdict says hedging would amplify moves, and the flip lies well above the price.
- 11:30 am. The Net is still negative, but the lean has slipped below 10%, so the page says Near balance and does not name a side. Net alone would have said amplifies; the lean says the strikes nearly cancel.
- 2:20 pm. Net is positive and the lean is 21%. The page says hedging dampens moves, and the price stands 109 points above the flip: on the side of the flip where the modelled hedging leans against moves.
Example 2: A Book That Amplifies
On the invented BANKNIFTY book at 2:20 pm the page reads Hedging amplifies moves, with Net −₹6712 Cr per 1% and the gamma flip at 55094, 1677 points from the price. The price is below the flip, on the side where the modelled hedging runs with each move. The flip lies about 3% above the price. With every strike drawn, the default, its badge and its rule are on the plot. Choose 11 strikes and the flip falls outside them, so its badge moves to the right edge with an arrow and has no rule.


Example 3: A Stock
A stock has a short chain and a ten-rupee strike step. On the invented RELIANCE book the page prints Hedging dampens moves, with Net ₹27.9 Cr per 1% (crore and lakh figures suit the size of the book) and the flip at 1341. All 15 strikes are drawn, so Customise dims the counts above 15, which would draw the same picture. The Measured over window opens on Day for a stock.


Example 4: Reading the Levels as Distances
At 2:20 pm the box lists 24700 (153 above), 24438 (109 below) and 24400 (147 below). What can be said, and no more: the price is between the two walls; it is above the flip; the nearest wall above carries the most Call hedging above the price; a move down of 109 points would put the price at the flip, and the model says the sign of the total changes there. What cannot be said: that the price will go there, that it will stop there, or that anyone will act.
Gamma Walls Against Open Interest Walls, and the Neighbouring Pages
How are gamma walls different from Open Interest walls, and how does this page relate to the Option Chain, Open Interest and PCR?
Several pages in the app mark a “wall”, and they do not all mean the same thing. This is the most common source of confusion between them.
| Where | Name | Rule (from the page's own text) |
|---|---|---|
| GEX Levels | Call gamma wall, Put gamma wall | The strike above (Call) or below (Put) the price with the largest gamma exposure on that side, across all strikes. |
| GEX Levels, Levels section | Call wall, put wall | The strike above or below the price with the most Open Interest. |
| Option Chain, detail panel | Call wall, Put wall | “Walls use the highest TOTAL Open Interest on each side of spot across the full expiry, not the day's change and not only the strikes on screen.” |
| Open Interest | Possible support, possible resistance | “The centre of the strongest scored cluster, not always the single tallest bar.” A different rule again. |
Why the Two Call Walls Differ Here
In the invented book the strike with the most Call Open Interest above the price is 25500: 270985 lots, against 158854 lots at 24700. Yet the Call gamma wall is 24700. The reason is gamma. Far above the price an option's gamma is small, so a great deal of Open Interest there still calls for little hedging.
Neither is wrong. They answer different questions: where is the largest standing position? and where would hedging be heaviest? On the Put side of the same book both rules name 24400, and the detail panel then labels the row Put gamma wall · put wall. When the two walls agree the page says so in one row; when they differ it prints two.

The Option Chain's Dealer Gamma Exposure Line
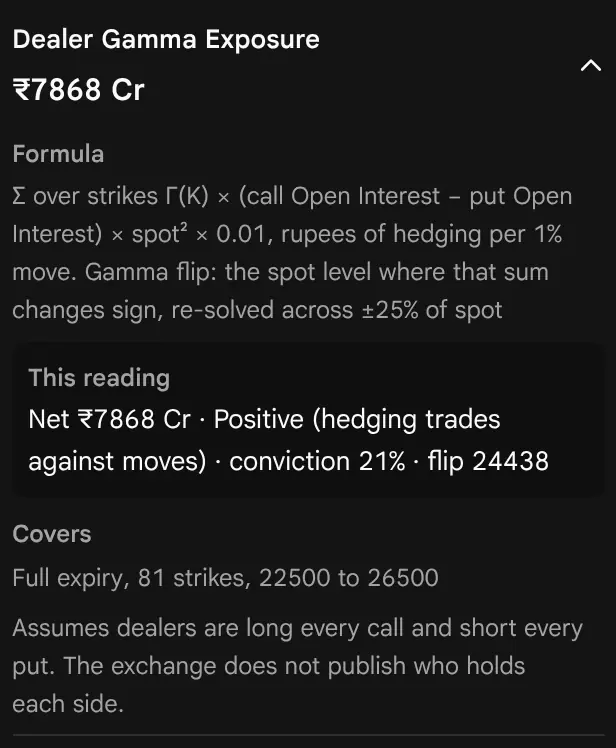
The Option Chain's insight detail carries one line, Dealer Gamma Exposure, built from the same model: the same formula, the same sign convention and a flip re-solved across 25% of the price. GEX Levels is the full page for it. For one snapshot the two surfaces use one forward and one time to expiry, so they print the same Net: in the pictures the Option Chain's line reads ₹7868 Cr and GEX Levels reads ₹7868 Cr. The match is for the same snapshot: the Option Chain follows the live chain and GEX Levels follows the saved reading you are looking at, so if the two are stamped at different times they will print different figures for that reason alone. (What we have not verified.)
The Flip Mark on the Strike Column
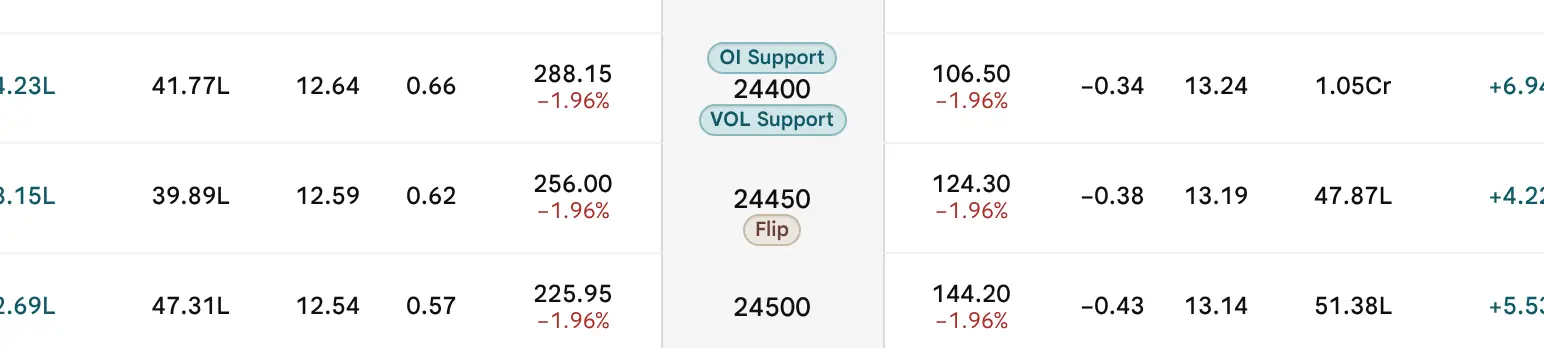
The Option Chain also marks the gamma flip on its strike rows. The strike nearest the flip carries a Flip capsule in the strike column. When that strike is also the at-the-money strike or the Max Pain strike, the marks share one capsule, for example ATM · Max Pain · Flip. The mark is placed from the same flip as the GEX Levels page (where the sign changes). It names a strike on the ladder, so it can sit up to half a strike step from the flip itself: the page prints the flip to the point, the chain rounds it to a strike. In the pictures the flip is 24438, and the chain puts its capsule on 24450.

The Gamma Column Is Not This Page's Gamma
The Option Chain can show a Gamma column for each leg. GEX Levels never uses it: it solves its own gamma from the traded price, one per strike, because a data provider's Call and Put gamma at one strike can disagree, and a sum over a whole ladder would carry the disagreement into the headline (where gamma comes from). A figure in that column and a figure on this page will not match, and are not meant to.


Where the Put Call Ratio Fits
The PCR page divides Put Open Interest by Call Open Interest and says nothing about price or time. Gamma exposure weights each strike by its gamma, so Open Interest near the price counts for a great deal and Open Interest far from it for little. Two books can have the same ratio and very different gamma exposure. In the pictures the Open Interest page prints a whole-expiry ratio of 0.64, below 1.00, which is a count of contracts across all strikes, while GEX Levels says hedging dampens moves, which is about the strikes near the price. They are separate questions, answered by separate pages. See the PCR guide and the Open Interest guide.
Routines
How do I use the page before the open, in the session, on expiry day and positionally?
These are ways to organise your reading. They are not signals and the page gives no advice.
Before the Open
- Open the page on the expiry you follow and read the stamp first: it tells you which reading you are looking at.
- Note the verdict, the lean and the flip's distance from the previous close.
- Note the Call and Put gamma walls, and the Open Interest walls on the Option Chain. Write the two sets side by side.
- Look at Gamma concentration: where would hedging be heaviest, whatever the sign?
During the Session
- Watch the 5m and 15m changes in the row. A rise or fall in Net is a change in the modelled book, not a trade.
- Watch the gist: how far the price is from the flip, and whether it has crossed.
- Use Price against these levels to see whether the price met a wall and turned or went through it.
- Use Session replay to look back at an earlier hour without leaving the page.
On Expiry Day
With less than 1 day to go, the page withholds its figures and says Not measured. That is the model declining, not a fault. Expiry-day questions belong to other pages: Open Interest and its walls on the Open Interest page, the premium and the move the market is pricing on the Straddle page, and the chain itself on the Option Chain. Use the next expiry in Customise to see how the book looks beyond today.
Positional Use
- Choose the expiry you hold in Customise and read it each morning. Keep a note of the verdict, the lean, the flip and the walls.
- Compare day to day with Day in Measured over. Remember the page's caution: gamma grows as expiry nears, so part of a change across sessions is the calendar.
- Compare expiries one after another. Hedging carried in other expiries is not seen by any single reading.
Common Mistakes and Risks
What do readers get wrong, and what should I check before I act?
- Reading positive as bullish. Positive means modelled hedging would steady the price. It says nothing about direction. The verdict is printed in plain ink for this reason.
- Forgetting the assumption. Every sign rests on the dealers-own-the-Calls assumption, which exchange data cannot confirm (part A). If you take away only one sentence from this guide, take that one.
- Treating the flip as a line the price must respect. It is a modelled level that moves with Open Interest, prices and time. It is not a support or resistance.
- Treating the verdict as a forecast. The words describe modelled hedging at one reading. The page does not claim they predict anything, and this guide has not tested them against later prices.
- Mixing up the walls. A gamma wall, an Open Interest wall and a possible resistance are three rules and can be three strikes (the table).
- Mixing up the flip and the ladder cross. The flip is where the book would change sign if the price moved; the ladder cross is where a running total crosses zero. In the pictures they are 623 points apart.
- Judging the levels from the strikes drawn. The levels use all strikes. A level off the plot is pinned with an arrow, not missing.
- Comparing rupee figures across underlyings. The price is squared in the formula. Compare the lean and the verdict instead.
- Reading a change in Net as new positions. A change can come from the price moving, the time passing, prices updating or the ladder gaining strikes, as well as from positions. The page says so in its cautions.
- Trusting a gamma from an old price. The gamma comes from last traded prices. At a strike that has not traded lately the price may be old, and the page has no way to know.
- Using it on expiry day. The page withholds its figures then. A figure from an earlier day does not describe the book on expiry day.
Checks Before You Rely on a Reading
- Have I read the first caution in the box?
- Is the lean above 10% by a margin, or just over it?
- Are the levels I am looking at gamma levels or Open Interest levels?
- Is the time to expiry short enough that gamma is swinging?
- Is the stamp recent, and is it the reading I meant to look at?
Where the Data Comes From, and How Old It Is
Where do the readings come from, how old are they, and what is not on the page?
- Saved readings. The page is built from saved readings of the option chain for the symbol and expiry, about one a minute through the session (the box calls them the minute snapshot archive). The page re-reads that archive about every 60 seconds while the market is open and the tab is visible. The newest reading is the one shown, and its time is in the stamp.
- The chain. The option chain itself is fetched about every 5 seconds in market hours. It feeds the header, and it is the single reading the page works from when there is no archive.
- Prices are last traded. Gamma is solved from the last traded price at each strike, so a strike with no recent trade carries an older price.
- The page is polled, not streamed. The figures change when a new reading arrives, not tick by tick.
- Time to expiry. The page counts it to the derivatives close, 15:40 from 3 August 2026 (what we have not verified).
- Previous close. Today and Day use the previous session's close of the same expiry when the archive holds it.
Which Tool When
When should I use this page and when another?
| My question | Use | Why |
|---|---|---|
| Would hedging in the open book lean against moves or run with them, and where does it change? | GEX Levels | It is this page's one job. |
| Where is Open Interest largest, and how has it changed? | Open Interest (guide) | Open Interest by strike with its own levels. |
| Is the Put to Call split of the book above or below one, and how has it moved today? | PCR (guide) | One ratio through the day. |
| What does each cell of the chain say? | Option Chain (guide) | Every price, Open Interest and Greek per strike. |
| How much is the market paying for a move, and how fast does that decay? | Straddle (guide) | The at-the-money premium and the move it implies. |
| Is implied volatility high or low against its past? | Implied Volatility (guide) | Volatility by strike, expiry and year. |
| Where are positions being added or cut quickly? | OI Spurts (guide) | Open Interest bursts. |
| What is happening on expiry day? | The Option Chain and Open Interest | GEX Levels withholds its figures on expiry day. |
Using It on a Phone
How do I use the page, and this guide, on a phone?
At or below 768 pixels wide the page uses its phone layout. The plot view capsule stays on the page bar (the bar pans sideways if it is too narrow). The strike count opens on All, as on a desktop; the counts 11, 15, 21, 31 and 41 are in Customise. The Customise button leaves the page bar and Customise opens from the settings button in the top bar. The insight opens as a sheet over the page with a close button. A tap on a bar pins it.
Reading It on a Phone
- The level names sit above the plot, not over the bars. The vertical rules for the levels stay on the plot. One key row above it lists the levels left to right, as the rules fall, with short names and strikes: Put wall, Flip, Spot, Call wall and Cross (the ladder cross). Each name has a short stroke drawn like its rule, so you can match a name to its line.
- A level outside the strikes drawn keeps its name in the key with an arrow, ← or →, and has no rule on the plot.
- The legend and the scope line sit under the plot: Call-dominant strike, Put-dominant strike, GEX per 1% move, and the line naming the expiry, the reading and the strikes drawn.
- Read one strike by tapping its bar. The card stays in the corner of the plot; tap the same bar again to let it go.



This Guide on a Phone
- A picture wider than the screen scrolls sideways inside its frame; a line above it says Swipe sideways to see all of it. Press Enlarge to open it full size.
- Tables scroll sideways in the same way. Both can be reached with the keyboard.
- Print the guide for a short, light version of it with the pictures in the light theme.
What the Page Cannot Tell You
What does the page not do?
- Who holds the contracts. The central limit. Open Interest has no holder; the signs are an assumption.
- Where the price will go. The verdict is about modelled hedging, not direction, and has not been tested against later prices.
- Whether anyone will hedge as modelled. It assumes dealers hedge their books and do so in the manner described. We cannot confirm that they do.
- Hedges outside the expiry shown. One expiry at a time; other tenors are not summed.
- Hedges outside the options book. Futures, cash positions and anything else a dealer holds are not seen.
- What happens on expiry day. The page declines to give a figure then.
- Anything finer than a minute. The readings are saved about once a minute and the page is polled.
- An order or a recommendation. The page places no order and gives no advice.
What We Have Not Verified
Which statements in this guide could we not confirm, and what should I check myself?
Everything in this guide about how the page behaves was read from the page's own program code or taken from a picture of the page. The items below are the ones we could not confirm. Where the guide touches one of them it links here instead of stating it as fact.
| What | What we do not know | What you can do |
|---|---|---|
| Who holds the contracts | The sign convention (Calls positive, Puts negative) assumes dealers own the Calls and are short the Puts. The page says so and so do we. Exchange data records Open Interest, never holders, so neither the page nor this guide can confirm it. | Read every signed figure as a conditional. Use the Gamma concentration view and the levels as the parts that do not depend on it. |
| That dealers hedge as the model describes | The table in part A (long gamma sells into rises and buys into falls) is the textbook picture. We did not observe any dealer, and we did not measure how much of the open book is hedged this way, or how quickly. | Treat the verdict as a description of modelled hedging, not a description of what happens. |
| Whether the verdict words predict anything | The page does not claim that the verdict predicts the price, and we have not tested it against later prices. We state no hit rate. | Use it as a description of the book at one reading. |
| Other names for the flip | The glossary says the gamma flip is sometimes called the zero-gamma level. We did not survey other sources, and this guide does not say who uses which name. | On this page, look for the words Gamma flip. |
| Whether the Option Chain and this page agree at every moment | For one snapshot the two surfaces print the same Net and the same flip, because they share one forward and one time to expiry (in the pictures both read the same figure). We checked this on the invented book, and the program's own tests check it on a stored reading. We did not check it on a live chain, whose own stamp can differ from the saved reading this page shows. | Compare them only when both are stamped at the same time. |
| How often a minute snapshot is saved | The page reads saved readings, about one a minute. The saving is done by a collector outside this program, so we have not confirmed that it runs every minute, or what it does when it is late. The page re-reads the archive about every 60 seconds; the collector's own cadence is not in the program. | Count the points on the session cards, or read the stamp. |
| The derivatives close at 15:40 and the expiry settle time | The page treats the derivatives session as ending at 15:40 from 3 August 2026 and at 15:30 before, and counts the time to expiry to that moment on the expiry date. We have not cited an exchange circular for it. The rule that the page withholds its figures under one day to expiry is the page's own. | Check the exchange's own notices for the close and the expiry time. |
| The interest rate | The model uses a fixed rate of 6.5%, a setting of the app. We did not check it against any market rate. | It affects the forward and the gamma slightly; it is not read from anywhere. |
| Lot sizes, strike steps, expiry weekdays and which expiries exist | The pictures use invented expiries (13, 20 and 27 October 2026), lot sizes taken from the app's list for the illustration and strike steps made for the book. We state no exchange rule about which weekday an expiry falls on, how many strikes are listed or what a lot is today. Lot sizes change over time. | Read the lot size and the expiries on the exchange's site or in the app. |
| Open Interest in units, not contracts | The page's data holds Open Interest as units of the underlying (contracts times lot), which is why the formula has no lot-size term. We checked this against the program's own notes and the figures in the pictures, not against an exchange document. The page warns when its values do not look like whole lots. | If the box carries the units caution, read the rupee totals with care; the flip and walls are unaffected. |
| The tolerance of the 5m and 15m comparisons | The page accepts an earlier reading only if it is close enough to five or fifteen minutes back. We did not state the exact tolerance. | Read the snapshots matched in the 5 min, 15 min and Today section of the detail panel. |
| Touch and keyboard behaviour on every device | We read the touch and keyboard handling from the code and tried the phone layout at phone size. We have not tried every phone, browser or assistive technology. | If a control does not respond as described, use the button on the page. |
| General statements about options and dealers | Statements such as how a dealer who is long or short gamma hedges, and why gamma grows near expiry, are textbook descriptions. We did not measure them from this page's data. | Treat them as background. |
| Pictures taken before the page changed | On 19 October 2026 the page changed in three ways the pictures do not show. The wall badges are in sentence case: Call gamma wall and Put gamma wall, no longer in capitals. On a phone the level badges no longer stack over the bars: the rules stay on the plot and one key row above it names them with short names and strikes. The closed insight row prints one short line saying how far the price is from the flip. These pictures were taken before that change and have not been retaken, so they still show the earlier page: The GEX Levels page as it opens, The readout for 24700, The Net view, The Call vs Put view, The Gamma concentration view, A pinned strike, The same day at 11:17 am, The closed insight row, One reading only, Strikes set to 11, Strikes set to All, BANKNIFTY: amplifying, RELIANCE on the same page, The page on a phone, A pinned strike on a phone. The text describes the page as it is now. | Trust the text where it differs from a picture, and read the badges on the page itself. |
| The other pages' own rules | The Option Chain, Open Interest and PCR pages are described only as far as their walls, Dealer Gamma Exposure line and ratios go. For everything else see their own guides. | Open the guides linked in Which tool when. |
Glossary
What does each word mean?
- Option, Call, Put
- A contract that gives its holder a right, not an obligation. A Call gives the right to buy the underlying at a fixed price, the strike; a Put gives the right to sell it. The page writes Call and Put. The exchange codes CE and PE mean the same.
- Underlying
- The index or share an option is written on, for example NIFTY, BANKNIFTY or RELIANCE.
- Strike
- The fixed price named in an option contract. An option chain lists one row per strike, with the Call on one side and the Put on the other.
- Expiry
- The date on which an option contract ends. The page reads one expiry at a time and prints it, for example 13 Oct.
- Open Interest
- The number of contracts at a strike that are still open: bought and sold but not yet closed or expired. It counts positions, not trades. It does not say who holds them. The page writes it in full.
- Lot
- The number of units one contract covers. The page works in units of the underlying, which is contracts times the lot, so the formula has no lot-size factor.
- Delta
- How many rupees an option's price moves for a one-rupee move in the underlying.
- Gamma
- How fast delta changes as the price moves: delta per point. It is largest near the money and falls away far from the price. The page works out one gamma for each strike.
- Hedging
- Buying or selling the underlying to cancel the price sensitivity of options held. How much a dealer must trade for a given move depends on gamma.
- Dealer
- Whoever holds the other side of the public's options and hedges it. The page assumes that dealers own the Calls and are short the Puts. Nobody can confirm that from exchange data.
- Modelled
- Worked out by the page's model under its assumptions, not observed. Every signed figure on the page is modelled.
- Gamma Exposure (GEX)
- For one strike: gamma × Open Interest × price² × 0.01, in rupees of hedging per one per cent move. Calls count positive and Puts negative.
- GEX per 1% move
- The unit of every figure: rupees of the underlying a hedger would trade if the price moved one per cent.
- Call GEX, Put GEX, Net, Both sides
- Call GEX is never negative; Put GEX is never positive; Net is their sum; Both sides adds the sizes of the two and assumes no holder.
- Lean
- The size of the total Net divided by the sum of the sizes of each strike's Net: how much of the strike-by-strike exposure survives adding the strikes up. 10% or more names a side; under it the page says Near balance. The Option Chain calls it conviction.
- Verdict
- One of Hedging dampens moves, Hedging amplifies moves, Near balance or Not measured. A regime, not a direction, and not a forecast.
- Gamma flip (zero gamma)
- The price at which the model's Net changes sign, found by re-pricing the whole book at candidate prices. Sometimes called the zero-gamma level. It is solved, not read off the bars, and it need not be a strike.
- Ladder cross
- The strike where the running total of Net, added from the lowest strike upward, crosses zero. A display device; a different level from the gamma flip.
- Call gamma wall, Put gamma wall
- The strike above the price with the largest Call GEX, and the strike below it with the largest Put GEX. Where the modelled book is thick, not a price that must hold.
- Call wall, put wall (Open Interest)
- The strike above or below the price with the most Open Interest. The Option Chain uses the highest total Open Interest on each side of the price across the expiry. Not the same as a gamma wall.
- Heaviest strike
- The strike with the largest Both sides figure: the most gamma, either side of the price. It does not depend on the holder assumption.
- Forward
- The price the market implies for the underlying at expiry, worked out from Call and Put prices at the strikes nearest the price.
- Implied volatility
- The volatility at which a pricing model reproduces an option's traded price. The page solves one for each strike and uses it to compute that strike's gamma.
- Coverage
- The share of all Open Interest that sits at strikes with a gamma. Under 60% the page offers no total; 95% or more passes the coverage check.
- Scope line
- The sentence under the profile naming the expiry, the reading and the strikes drawn. A phone always shows it; a desktop shows it only while the replay is on an earlier reading.
- Level key (phone)
- On a phone, the one row above the strike plot that names the levels left to right with short names and strikes: Put wall, Flip, Spot, Call wall and Cross. The rules stay on the plot.
- Measured over
- The choice of 5 min, 15 min or Day for the change sentence of the insight box. It does not change the verdict.
- Session replay
- A strip, switched on in Customise, that steps the whole page back to an earlier reading of the session. Not remembered.
- Minute snapshot
- One saved reading of every strike of the chain, taken about once a minute. The page is built from these.
- At the money (ATM)
- The strike nearest the current price of the underlying.
- Days to expiry (DTE)
- The number of days left to the expiry, shown beside the expiry in Customise.
- Lakh, crore
- Indian units: a lakh is 100000 and a crore is 100 lakh (10000000). The page prints them as L and Cr, for example ₹7868 Cr.
Questions Readers Ask
What do readers ask most?
What is a good GEX value?
There is no good or bad value. The figure says whether modelled hedging would lean against moves (positive) or run with them (negative), and how strongly (the lean). It is not a signal.
Does positive gamma mean bullish?
No. Positive means the modelled hedging steadies the price: it sells into rises and buys into falls. The page prints the verdict in plain ink for that reason, and says positive gamma is stabilising, not bullish.
Who holds the Calls and Puts?
No one can tell from exchange data. The page assumes dealers own the Calls and are short the Puts, and says so on every reading. Part A works through what changes if that is wrong.
Why is there no lot size in the formula?
The page's Open Interest is in units of the underlying, which is contracts times the lot size, so the lot is already inside it. Multiplying again would inflate every figure.
Why is the price squared?
Because the figure is rupees of hedging for a one per cent move. A one per cent move is 0.01 times the price in points, and the quantity hedged is worth that quantity times the price. The factors.
What is the difference between the gamma flip and the ladder cross?
The flip is the price at which the whole modelled book would change sign, found by re-pricing it. The ladder cross is the strike where a running total of Net crosses zero. They answer different questions and can be hundreds of points apart. The levels.
Why is the Call gamma wall not the strike with the most Call Open Interest?
Gamma is small far from the price, so a large Open Interest there still calls for little hedging. The page picks the strike with the largest gamma exposure above the price. Part D.
Why does the page say Near balance when Net is not zero?
Because the lean is under 10%: the strikes nearly cancel, so the sign of the total carries little. The page declines to name a side.
Why does the page say Not measured?
It gives the reason in words: less than a day to expiry, a settled series, too little of the book with a usable price, or no Open Interest. The list.
Why are the 5m, 15m and Today figures dashes?
There was no earlier reading close enough to compare with. A dash is not zero, and the reason is given in words.
Why did the levels not change when I chose fewer strikes?
The levels are always worked on all the strikes of the expiry. The strike count changes only what is drawn.
Why does the page not work on expiry day?
Under a day to expiry, gamma swings by more than the figure itself, so the page withholds its figures rather than print a number it does not trust.
Does the Option Chain show the same Net as this page?
For the same snapshot, yes. Its Dealer Gamma Exposure line uses the same model on the same forward and time to expiry, so in the pictures both print the same Net and the same flip. If the live chain and the saved reading are stamped at different times, they print different figures. What we have not verified.
Does the Option Chain mark the gamma flip?
Yes. The strike nearest the flip carries a Flip capsule in the strike column, joined to ATM or Max Pain when they share the strike (for example ATM · Max Pain · Flip).
Does the page use the Gamma column of the Option Chain?
No. It solves its own gamma, one per strike, from the traded price.
Are my settings saved?
In this browser: the plot view, the two Levels switches, the strike count you chose and the Measured over choice. The expiry is not reset by Reset. The replay is never saved.
Does the page place orders or give advice?
No. It describes modelled hedging and nothing more.
Are the numbers in this guide real prices?
No. The pictures use an invented market made for the guide. The figures show how the page works, not what the market is.
Sources
Where does each statement in this guide come from?
The guide rests on the program code of the GEX Levels page and on pictures of the page itself. The constants below are quoted in the text from one list (scripts/guides/gamma-exposure-parts/limits.mjs), and the build fails if a constant is no longer found in the file named beside it. Exchange rules are not stated.
Where Each Part Comes From
| Part of the guide | Source files |
|---|---|
| The formula per strike, the sign convention, the sums, the lean and the verdict word | src/lib/gex.ts (computeGexProfile, strikeGamma, resolveWalls, GEX_BALANCED_BAND); src/features/gex/gexInsight.ts (gexVerdictOf, leanText) |
| Where the gamma comes from: the traded price, the implied volatility, the forward, the time left | src/lib/gexSeries.ts (chainFromSnapshot, parityForward); src/lib/impliedVol.ts; src/lib/optionPricing.ts (blackScholesGreeks, DEFAULT_RISK_FREE_RATE) |
| The gamma flip, the ladder cross, the curve | src/lib/gex.ts (netGexAtSpot, solveFlip, cumulativeCrossStrike, gexCurveBetween); src/features/gex/GexPlots.tsx (GexCurvePlot) |
| The gamma walls, the heaviest strike | src/lib/gex.ts (resolveWalls, absGammaStrike) |
| The strike profile, its three views, badges, readout and table | src/features/gex/GexPage.tsx; src/features/gex/GexPlots.tsx; src/features/gex/gex.css |
| The session charts and the replay | src/features/gex/GexSessionCharts.tsx; src/lib/gexSeries.ts (buildGexSeries); src/components/common/SessionReplay.tsx |
| The insight row, box and detail panel | src/features/gex/gexInsight.ts; GexInsightCard.tsx; src/components/insights/InsightCard.tsx, InsightWindowControl.tsx, InsightMovement.tsx; src/lib/insightWindow.ts, insightMovement.ts |
| Customise and what is remembered | src/features/gex/GexCustomizePanel.tsx; gexCustomiseSettings.ts; src/lib/remembered.ts |
| Where the readings come from and how often | src/App.tsx (gexSnapshots, SNAPSHOT_REFRESH_INTERVAL_MS, usePreviousClose); src/hooks/useOptionChain.ts; src/components/insights/usePreviousClose.ts |
| The states: loading, withheld, thin, error | src/features/gex/GexPage.tsx; src/features/gex/gexInsight.ts (causeOf); src/lib/gex.ts (GexProblem) |
| Phone layout | src/features/gex/gex-phone.css; src/features/gex/gexCustomiseSettings.ts (useGexPhoneLayout); src/App.tsx (Customise from the top bar) |
| The pictures | scripts/guides/shot-gamma-exposure.cjs; scripts/guides/gamma-exposure-mock.cjs; scripts/guides/gamma-exposure-parts/figures.json; calc.json (build-gex-calc.mjs) |
The Numbers the Guide Quotes
| Number | What it is | Source file |
|---|---|---|
| 0.01 | The factor in the formula: Gamma × (Call Open Interest − Put Open Interest) × spot² × 0.01, rupees per 1% move | src/lib/gex.ts |
| 10% | A lean under this reads Near balance; at or above it the page names a side | src/lib/gex.ts |
| 25% | How far either side of the price the flip is searched, as a share of the price | src/lib/gex.ts |
| 400 | Candidate prices tried across that range before each sign change is narrowed down | src/lib/gex.ts |
| 60% | Share of Open Interest that must sit at strikes with a gamma before any total is shown | src/lib/gex.ts |
| 95% | Share of Open Interest with a gamma at which the insight counts the coverage check as passed | src/features/gex/gexInsight.ts |
| 1 day | Under one day to expiry the page withholds the figures (gamma that close to expiry swings too much) | src/lib/gex.ts |
| 6.5% | The interest rate the model uses (a fixed setting of the app, not a market rate read from anywhere) (not verified) | src/lib/optionPricing.ts |
| 11, 15, 21, 31, 41, All | The strike counts Customise offers | src/features/gex/gexCustomiseSettings.ts |
| All strikes, on a desktop and on a phone | The strikes drawn until a count is chosen | src/features/gex/gexCustomiseSettings.ts |
| 768 | At or below this width (CSS pixels) the page uses its phone layout | src/features/gex/gexCustomiseSettings.ts |
| 5 min, 15 min, Day | The Measured over choices (default 15 min for an index, Day for a stock) | src/lib/insightWindow.ts |
| 5 minutes | The session charts sample one reading in each five minutes, up to 120 points | src/lib/gexSeries.ts |
| 5 | The option chain is fetched again this often while the market is open and the tab is visible | src/hooks/useOptionChain.ts |
| 60 | The saved minute readings are read again this often while the market is open and the tab is visible | src/App.tsx |
| 15:40 | The derivatives session close the page uses for the time left to expiry (from 3 August 2026; 15:30 before) (not verified) | src/lib/marketSession.ts |
| gexView:v1, gexCustomise:v1 | What the page remembers in this browser (the plot view; the two Levels switches and the strike count). The replay is never remembered | src/features/gex/gexCustomiseSettings.ts |
| 90% | Open Interest must be a whole number of lots at nine in ten values or more, or the rupee totals carry a caution | src/lib/gex.ts |
The Pictures
Each picture is a capture of the real page on an invented market, taken on Monday 5 October 2026 at 2:20 pm (the page's clock was frozen at that moment), except the expiry-day picture (Tuesday 13 October at 11:30 am). They are regenerated with node scripts/guides/shot-gamma-exposure.cjs, and the market is made by scripts/guides/gamma-exposure-mock.cjs. The worked figures come from node scripts/guides/gamma-exposure-parts/build-gex-calc.mjs, which runs the page's own model on that market, and the build compares them with what the page printed.
Test Your Knowledge
Check the mechanics before you take them to a live chain.
1. In the formula Gamma × (Call Open Interest − Put Open Interest) × price² × 0.01, the price doubles while gamma and Open Interest stay as they are. What happens to the strike's Net?
2. The page counts every Call as positive and every Put as negative. What is that the same as assuming?
3. If every sign were reversed (dealers short the Calls and long the Puts), which of these would NOT change?
4. In the pictures the lean at 11:30 am is under 10% although Net is negative. What does the page say?
5. The strike with the most Call Open Interest above the price is 25500, yet the Call gamma wall is 24700. Why?
6. What does the gamma flip measure?
7. You choose 11 strikes instead of All in Customise. What happens to the gamma flip and the walls?
8. It is expiry day at 11:30 am. What does the page show?
About the Sahi GEX Levels
Gamma exposure estimates how much hedging the open option book would generate for a given move in the underlying. It is computed strike by strike from open interest and a gamma solved from live premium, then expressed in rupees per one per cent move, so the figures stay comparable between one underlying and another.
The page marks the gamma flip — the level at which the measured total would change sign — along with the call and put gamma walls, the net reading and the shape of the book across every strike. One important caveat travels with every figure: who holds which side of the open interest is not published by any exchange, so the sign rests on a convention rather than an observation.
At a glance
- Data
- Saved minute readings of the option chain for one expiry, re-read about every minute; polled, not streamed
- Updates
- The chain is fetched about every 5 seconds while the market is open
- Coverage
- The underlyings the app lists: indices such as NIFTY and BANKNIFTY, and stock options. Read the list in the app
- Orders
- Analysis only. The page places no order
- Kept
- Your choices stay in this browser
- Pictures
- Real captures of the page on an invented market, for Monday 5 October 2026; several were taken before the page changed on 19 October 2026
See it on today's numbers
Everything above is method. These articles apply it to a live book — gex levels among the rest — and are rebuilt as the snapshot data refreshes. Where a symbol's option book is too thin to support a reading, the article says so rather than asserting a level.
Frequently asked questions
What is gamma exposure?
Gamma exposure is an estimate of how much of the underlying option writers would need to buy or sell to stay hedged as price moves. It multiplies each strike's gamma by the open interest sitting there, scaled so the answer reads as rupees per one per cent move. A large total means hedging flow is large relative to the move that triggers it.
What is the gamma flip level?
The gamma flip, also called the zero-gamma level, is the price at which the measured net gamma exposure would change sign. Above it the book is measured as net positive and hedging leans against each move; below it the book is net negative and hedging leans with it. This page finds it by recomputing gamma at candidate levels rather than by interpolating the strike profile, because the two methods can disagree by thousands of points on the same tape.
What are the call and put gamma walls?
The call gamma wall is the strike above spot carrying the most call-side gamma, and the put gamma wall the strike below spot carrying the most put-side gamma. They are weighted by gamma rather than by contracts, so they can sit on a different strike from the heaviest open-interest strike shown on the Open Interest page — gamma decays with distance from spot, and the two measures answer different questions.
Is gamma exposure reliable for NIFTY and BANKNIFTY?
It is weaker here than the American research it comes from. That work assumes dealers are long calls and short puts, which follows from United States customers buying protective puts and writing calls. Indian participant data does not show a stable book of that shape, and index options here are cash settled with heavy expiry-day volume. The absolute gamma reading, which does not assume who holds what, is the part that survives if the convention does not hold.
Where does this data come from?
Open interest and traded premium come from the same session snapshots the rest of this site uses. Gamma is not taken from the feed: it is recomputed per strike from a volatility solved off the traded price, because a strike's call and put must share one gamma and vendor-reported values here do not always agree. Readings are suppressed rather than estimated once a series has settled.
Is the data on Sahi live or delayed?
The option chain is re-fetched about every 5 seconds while the market is open; it is polled, not streamed. Greeks and implied volatility are computed from those quotes. Outside market hours the last completed session is shown.
Read next
Explore more Sahi tools
Every tool runs on the same market data and keeps whichever instrument you have selected, so you can move between them without re-picking the symbol.
Option Chain
Scan and build
Every Sahi guide
Each guide pairs with a live tool. The options FAQ collects every question from all of them in one place.